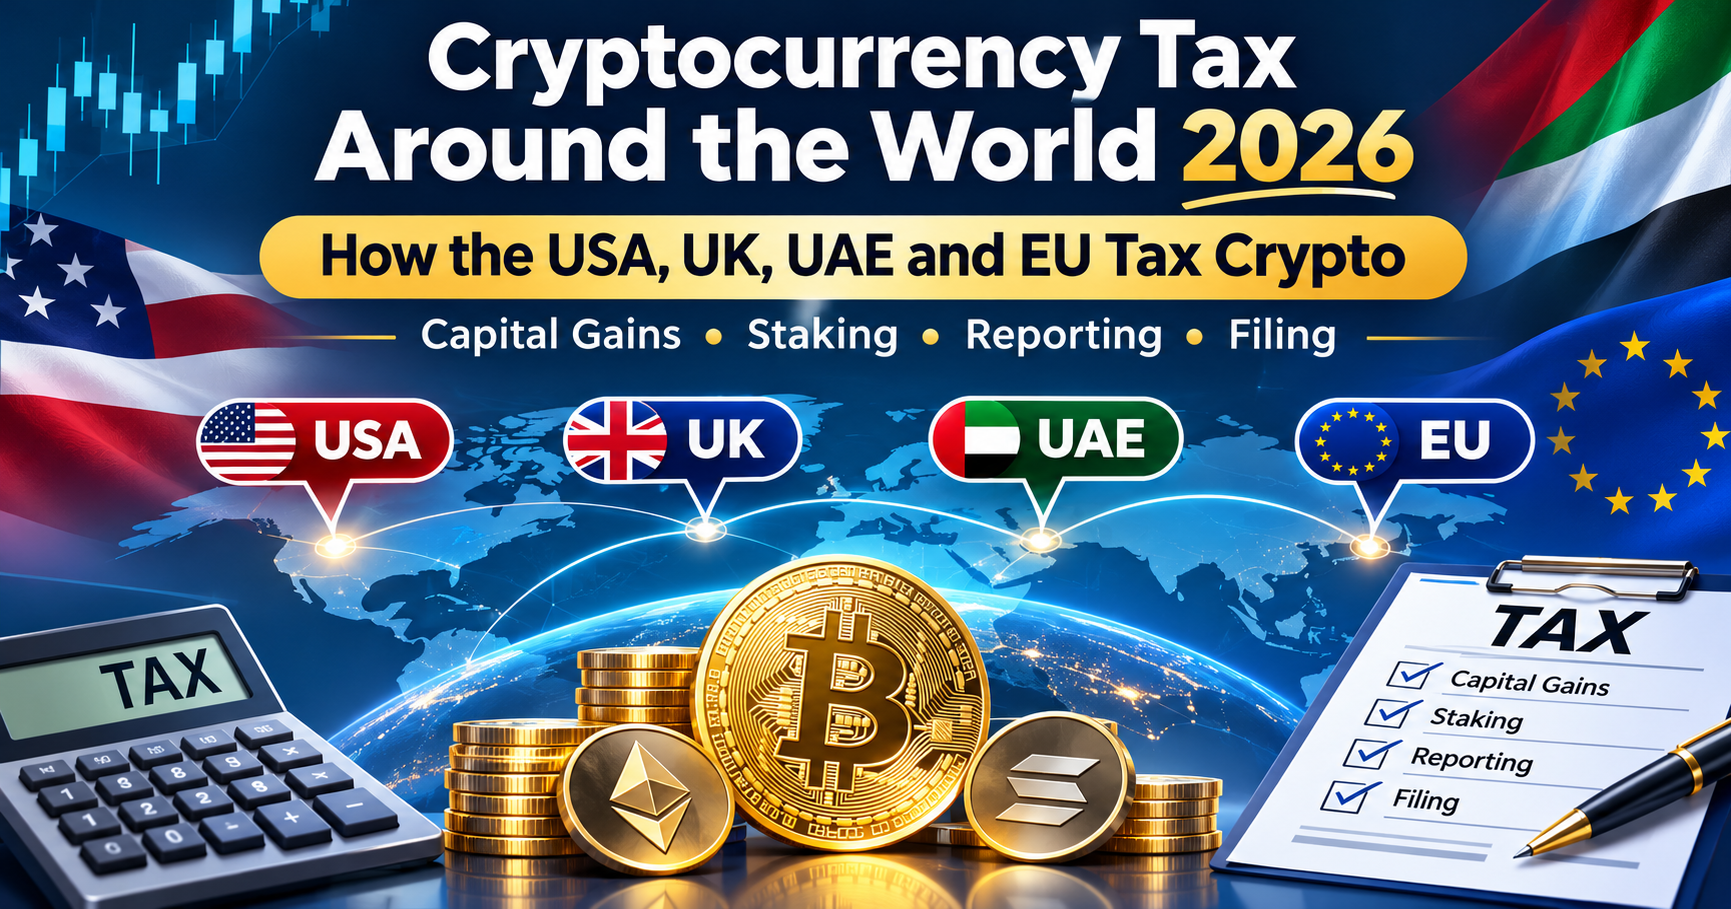
Cryptocurrency Tax Around the World 2026: How the USA, UK, UAE and EU Tax Crypto
Published: November 10, 2026
Coverage: United States, United Kingdom, United Arab Emirates and European Union
Tax Year: 2026
Relevant Authorities: IRS, HMRC, UAE Federal Tax Authority and EU Member State Tax Authorities
Cryptocurrency has become an important part of the global financial system. Investors increasingly hold Bitcoin, Ethereum, stablecoins and other digital assets for investment, payments, trading, staking and business activities.
However, cryptocurrency taxation is not the same in every country.
In the United States, digital assets are generally treated as property for federal income tax purposes. Selling or exchanging cryptocurrency can create capital gains or losses.
In the United Kingdom, most individual crypto investors are subject to Capital Gains Tax when they dispose of cryptoassets at a taxable gain.
The United Arab Emirates generally does not impose federal personal income tax on genuine private investment gains, but business activities may fall within Corporate Tax rules.
The European Union has no single cryptocurrency income tax rate. Individual member states determine their own taxation systems, while new EU-wide reporting rules improve transparency.
This comprehensive guide explains crypto tax rules for 2026, including taxable transactions, capital gains calculations, staking income, mining activities, exchange reporting, tax exemptions and the latest international reporting developments.
1. Is Cryptocurrency Taxable in 2026?
Yes, cryptocurrency transactions can be taxable in many countries.
However, tax depends on several factors:
- The taxpayer's country of tax residence.
- The type of cryptocurrency transaction.
- Whether the asset is held as a personal investment or business inventory.
- The original acquisition cost.
- The selling price or disposal value.
- The holding period.
- Income received from staking, mining or services.
- Applicable exemptions and deductions.
- Local tax laws.
Simply owning cryptocurrency does not ordinarily mean the investor must pay income tax on its full market value every year.
However, selling, exchanging, spending or earning cryptocurrency can create tax obligations.
Taxpayers should distinguish between holding crypto, disposing of crypto and receiving new crypto as income.
2. Global Cryptocurrency Tax Comparison for 2026
| Jurisdiction | Main Personal Tax Treatment | Important Rule |
|---|---|---|
| United States | Capital gains or ordinary income | IRS treats digital assets as property |
| United Kingdom | Capital Gains Tax and Income Tax | Taxable disposals and crypto income |
| United Arab Emirates | No general personal income tax on genuine private investment gains | Business activities may fall under Corporate Tax |
| European Union | Member-state-specific tax rules | DAC8 introduces coordinated reporting |
| Germany | Special treatment may apply to qualifying private disposals | Holding period and transaction classification matter |
| France | Special rules apply to qualifying individual investors | Professional trading can be treated differently |
| Italy | Country-specific crypto gains rules | Current domestic law determines applicable rates and thresholds |
Important: The European Union is not a single income-tax jurisdiction. A rate applicable in one EU country should not be applied across all member states.
3. USA Cryptocurrency Tax Rules in 2026
The Internal Revenue Service (IRS) generally treats cryptocurrency and other digital assets as property for federal income tax purposes.
Digital assets can include:
- Bitcoin.
- Ethereum.
- Stablecoins.
- Certain non-fungible tokens.
- Other qualifying blockchain-based digital assets.
The general tax principles for property transactions apply to relevant digital asset transactions.
Common Taxable Cryptocurrency Events
- Selling Bitcoin for US dollars.
- Exchanging Bitcoin for Ethereum.
- Spending cryptocurrency on goods or services.
- Receiving cryptocurrency as business payment.
- Earning mining rewards.
- Receiving staking rewards.
- Disposing of digital assets at a gain.
A sale can result in a gain or loss, depending on the relevant tax basis and disposal proceeds.
Example: Bitcoin Capital Gain
An investor purchases Bitcoin for $20,000.
Later, the investor sells it for $30,000.
| Description | Amount |
|---|---|
| Bitcoin Cost Basis | $20,000 |
| Sale Proceeds | $30,000 |
| Capital Gain | $10,000 |
The illustrative capital gain is $10,000.
Actual taxable gain may differ after eligible transaction costs and tax-basis adjustments.
The tax rate depends on whether the gain is short-term or long-term and the taxpayer's income and filing status.
4. USA Short-Term vs Long-Term Crypto Capital Gains
For crypto held as a capital asset, the holding period is important.
Short-Term Capital Gains
A short-term capital gain generally arises when an asset is held for one year or less.
Short-term gains are generally taxed at the applicable ordinary federal income tax rates.
For 2026, federal ordinary income tax rates range from 10% to 37%.
Long-Term Capital Gains
A long-term capital gain generally arises when an asset is held for more than one year.
For many individual taxpayers, the federal long-term capital gains rates are:
- 0%.
- 15%.
- 20%.
The applicable rate depends on taxable income and filing status.
Additional taxes, including the Net Investment Income Tax, may apply in qualifying circumstances.
State-level taxes may also apply.
Important: A 15% capital gains rate is not automatically applicable to every US crypto investor.
5. IRS Form 1099-DA: New Cryptocurrency Reporting in 2026
Form 1099-DA is an important development in US cryptocurrency tax reporting.
It is used by relevant digital asset brokers to report certain sales and exchanges.
The IRS introduced phased broker reporting requirements.
Key Reporting Changes
Transactions from 2025: Relevant brokers began reporting gross proceeds for covered digital asset sales.
Transactions from 2026: Relevant brokers are generally required to report additional tax-basis information for covered digital assets.
However, the basis reporting rules do not apply identically to every cryptoasset or transaction.
Important for Investors
Receiving Form 1099-DA does not mean the entire reported sale proceeds are taxable profit.
Investors generally need to calculate their gain or loss using the legally relevant cost basis.
Taxpayers must also report taxable crypto transactions even when they do not receive a Form 1099-DA.
6. How to Report Cryptocurrency on a US Tax Return
For capital asset transactions, individual taxpayers generally use:
Form 8949: Sales and Other Dispositions of Capital Assets.
Schedule D: Capital Gains and Losses.
Other digital asset income may be reported using different forms or schedules.
For example:
- Non-business staking income may be reported as other income.
- Mining conducted as a business may require Schedule C.
- Employment compensation paid in crypto may be reported as wages.
- Independent contractor income paid in crypto may be business income.
The correct form depends on the actual transaction.
Taxpayers should answer the applicable digital asset question on their federal income tax return accurately.
7. Is Crypto-to-Crypto Trading Taxable in the USA?
Generally, yes.
Exchanging one cryptocurrency for a different cryptocurrency can create a taxable disposal.
Example
An investor purchases Bitcoin for $5,000.
The Bitcoin later increases in value to $8,000.
The investor exchanges it for Ethereum.
For illustration, the Bitcoin disposal creates a potential $3,000 capital gain.
The investor did not receive US dollars, but the exchange can still be taxable.
The Ethereum generally receives an acquisition basis determined under the applicable rules.
Therefore, switching from Bitcoin to Ethereum does not automatically defer income tax.
8. UK Cryptocurrency Tax Rules for 2026–27
HM Revenue & Customs generally treats many personal cryptoasset disposals as potentially subject to Capital Gains Tax.
The UK tax year runs from April 6 to April 5.
For Tax Year 2026–27, the ordinary individual Capital Gains Tax rates are generally:
| Rate Category | CGT Rate |
|---|---|
| Basic-rate portion | 18% |
| Higher-rate portion | 24% |
| Annual Exempt Amount | £3,000 |
The applicable rate depends on taxable income, gains and other statutory conditions.
The annual exempt amount generally applies to total qualifying capital gains, not separately to every cryptocurrency.
9. Which Crypto Transactions Are Taxable in the UK?
HMRC identifies several types of disposals that can create capital gains or losses.
These include:
- Selling cryptocurrency for fiat currency.
- Exchanging one cryptoasset for another.
- Spending cryptoassets on goods or services.
- Gifting cryptoassets to someone other than a qualifying spouse, civil partner or charity.
Example: UK Bitcoin Sale
An investor buys cryptocurrency for £10,000.
Later, the asset is sold for £20,000.
The illustrative gain is £10,000 before allowable costs or other adjustments.
Assume:
- The person has no other chargeable gains.
- The full £3,000 annual exemption is available.
- All remaining gains fall within the 18% CGT band.
Taxable gain:
£10,000 − £3,000 = £7,000.
Illustrative CGT:
£7,000 × 18% = £1,260.
The actual calculation may depend on HMRC's cryptoasset matching and pooling rules and the person's wider tax position.
10. UK Cryptoasset Pooling and Cost Basis
HMRC applies specific rules for calculating gains on many fungible cryptoassets.
These can include:
- Same-day matching rules.
- The 30-day matching rule.
- Section 104 pooling.
Investors should not automatically calculate each sale using whichever purchase price produces the lowest tax.
Example
A person buys the same cryptocurrency on several dates at different prices.
When part of the holding is sold, the allowable cost may need to be determined using HMRC's matching rules rather than one arbitrary acquisition price.
Accurate transaction records are essential.
11. UK Cryptocurrency Income From Mining and Staking
Not every crypto receipt is a capital gain.
HMRC states that cryptoassets received from activities such as mining, staking and some lending arrangements may be taxable as income.
The classification depends on the circumstances.
If the activity amounts to a trade, business income rules may apply.
If it does not amount to a trade, rewards may still be taxable as other income.
A later sale of the received cryptoassets can separately create a capital gain or loss.
This means receiving staking rewards and later selling those rewards may involve two separate tax events.
12. UK Cryptoasset Reporting Framework From January 2026
The UK introduced new Cryptoasset Reporting Framework requirements effective from January 1, 2026.
The rules require relevant cryptoasset service providers to collect specified customer and transaction information.
The framework is intended to improve transparency and the international exchange of cryptoasset tax information.
Important 2026 Reporting Details
- Reporting information is collected for relevant transactions from January 1, 2026.
- Relevant providers must perform customer due diligence.
- Providers may need to obtain tax residency and identification information.
- The first reporting deadline is May 31, 2027, according to HMRC's latest guidance.
HMRC updated the reporting guidance in November 2026, including changes concerning the availability of its online reporting service.
Important: These provider reporting rules do not replace an individual's own responsibility to report taxable income and gains.
13. UAE Cryptocurrency Tax Rules in 2026
The United Arab Emirates has a different personal tax system from the United States and United Kingdom.
The UAE does not impose a general federal personal income tax on individuals.
As a result, genuine private cryptocurrency investment gains are generally not subject to a separate federal personal income tax or personal capital gains tax.
However, business activities can create different obligations.
Private Investor Example
An individual resident in Dubai purchases Bitcoin for AED 50,000.
The individual later sells it for AED 80,000 as part of genuine personal investment activity.
The mathematical gain is AED 30,000.
Under the UAE's general personal income tax framework, such genuine private investment gains are generally not subject to federal personal income tax.
Important: Tax residency, the actual nature of the activity and obligations in other countries must still be considered.
14. UAE Corporate Tax on Crypto Businesses
The UAE Corporate Tax system can apply to companies conducting crypto-related business activities.
Under the ordinary regime:
| Taxable Income | Standard Corporate Tax |
|---|---|
| First AED 375,000 | 0% |
| Amount above AED 375,000 | 9% |
The calculation concerns taxable income, not gross crypto trading volume.
Example
Assume a crypto-related company has AED 1,000,000 in taxable income.
Under the standard rates:
AED 1,000,000 − AED 375,000 = AED 625,000.
AED 625,000 × 9% = AED 56,250.
Illustrative Corporate Tax: AED 56,250.
This assumes the standard rules apply and ignores other adjustments, exemptions or special regimes.
Qualifying Free Zone Persons may have different treatment.
Natural Persons Conducting Business
For individuals conducting a business in the UAE, Corporate Tax rules may apply when relevant business turnover exceeds AED 1 million in a calendar year.
However, personal investment income is generally excluded from the natural-person business-activity test where the applicable conditions are satisfied.
A professional crypto trader or crypto business operator should not automatically assume that every activity qualifies as private investment.
15. Is Cryptocurrency Subject to UAE VAT?
The UAE's VAT Executive Regulation was amended through Cabinet Decision No. 100 of 2024.
The amendments expanded specified financial-services exemptions involving virtual assets.
The transfer and conversion of qualifying virtual assets generally receive VAT-exempt treatment under the relevant provisions.
However, not every service connected to cryptocurrency is automatically exempt.
Different treatment may apply to:
- Crypto mining services.
- Platform services.
- Advisory services.
- Certain custody or management arrangements.
- Other taxable commercial services.
The correct VAT treatment depends on the specific transaction and statutory requirements.
An exemption from VAT does not automatically mean exemption from Corporate Tax.
16. Is Cryptocurrency Legal and Regulated in the UAE?
Cryptocurrency investment taxation and virtual asset regulation are separate legal matters.
The UAE has introduced various regulatory arrangements for virtual asset services.
Relevant regulators may include:
- Dubai's Virtual Assets Regulatory Authority (VARA).
- The Securities and Commodities Authority.
- Relevant financial free-zone regulators.
- Other competent authorities.
Businesses operating cryptocurrency exchanges, brokerage services or virtual asset platforms should verify applicable licensing obligations.
A low-tax environment does not remove licensing, anti-money-laundering or compliance responsibilities.
17. European Union Cryptocurrency Tax Rules in 2026
The European Union does not impose one uniform personal income tax rate on cryptocurrency gains.
Each member state determines the applicable domestic tax treatment, subject to EU law.
For example, crypto tax rules may differ between:
- Germany.
- France.
- Italy.
- Spain.
- The Netherlands.
- Portugal.
- Ireland.
Some countries treat certain cryptocurrency sales as private capital gains.
Others apply special holding-period, income tax, investment taxation or business taxation provisions.
Therefore, it would be misleading to describe cryptocurrency as subject to one universal EU tax percentage.
18. Germany: Cryptocurrency Tax Overview
Germany has specific rules affecting private cryptocurrency transactions.
For qualifying privately held cryptoassets, the holding period can be especially important.
A private sale after more than one year may fall outside the relevant taxable private disposal rules where the statutory conditions are satisfied.
Sales within a shorter period may create taxable income, subject to the relevant conditions and exemptions.
However, treatment can differ for:
- Commercial crypto trading.
- Staking rewards.
- Mining.
- Business-owned digital assets.
- Other income-generating arrangements.
Taxpayers should check current German tax guidance before relying on a holding-period exemption.
19. France: Cryptocurrency Tax Overview
France has a specific tax framework for individual cryptocurrency transactions.
Qualifying occasional or non-professional disposals may be subject to a flat-tax framework, although elections and updated social-contribution rules can affect the effective burden.
Professional crypto trading can receive different treatment.
A taxpayer must distinguish:
- Private investment disposals.
- Professional trading.
- Mining or business activity.
- Qualifying taxable exchanges.
- Relevant reporting requirements.
The correct tax calculation should be based on the rules applicable to the disposal date.
20. Italy, Spain and Other EU Countries
Other EU countries maintain distinct domestic taxation rules.
Italy
Italy has specific rules for taxation of cryptoasset gains and relevant reporting requirements.
Changes in domestic rates and thresholds should be checked for the 2026 tax year.
Spain
Spain generally taxes relevant cryptocurrency gains under the applicable savings-income framework.
Additional asset and foreign-holding reporting requirements can arise.
Portugal
Portugal provides specific rules for certain cryptocurrency transactions, including potentially different treatment depending on holding periods and the nature of the activity.
Netherlands
The Netherlands has a different framework for certain private investment assets, and its treatment should not simply be equated with a conventional capital gains tax.
Important: These examples illustrate different legal approaches. They are not a substitute for checking each country's current tax rates, holding-period rules and return requirements.
21. EU DAC8: New Cryptocurrency Tax Reporting From 2026
One of the most important developments for European cryptocurrency investors is DAC8.
DAC8 is the eighth amendment to the European Union's Directive on Administrative Cooperation in taxation.
It expands automatic exchange of information to include reportable cryptoasset transactions.
Important DAC8 Dates
| Requirement | Date |
|---|---|
| DAC8 Rules Apply | January 1, 2026 |
| First Transaction Reporting Period | Calendar Year 2026 |
| First Reporting and Information Exchange Cycle | 2027 |
| EU Information Exchange Deadline | September 30, 2027 |
DAC8 requires relevant reporting cryptoasset service providers to collect and report specified transaction and taxpayer information.
The framework covers a broad range of relevant assets and transactions.
What DAC8 Means for Investors
Crypto exchanges may need to collect information concerning:
- Tax residency.
- Tax identification numbers.
- Identity details.
- Reportable cryptocurrency transactions.
- Relevant transaction values.
- Other prescribed information.
Tax authorities may exchange this information with other member states.
Does DAC8 Create a New EU Crypto Tax Rate?
No.
DAC8 concerns tax transparency and information exchange.
The tax payable on cryptocurrency continues to depend on the domestic tax law of the relevant country.
22. What Is the OECD Crypto-Asset Reporting Framework?
The Crypto-Asset Reporting Framework, commonly called CARF, is an international information-reporting standard developed by the OECD.
Its purpose is to improve international tax transparency involving digital assets.
The framework establishes requirements concerning:
- Reporting service providers.
- Relevant cryptocurrency transactions.
- Taxpayer identification.
- Tax residency.
- Information exchange between tax authorities.
CARF does not itself impose a universal cryptocurrency capital gains tax.
Countries implement the applicable reporting framework through their domestic legislation.
The UK and EU have introduced relevant crypto reporting measures beginning in 2026.
Other jurisdictions may follow different implementation schedules.
23. Are Cryptocurrency Swaps Taxable?
A cryptocurrency swap occurs when one digital asset is exchanged for another.
The tax treatment differs by country.
USA
Crypto-to-crypto swaps generally create taxable property disposals.
UK
Exchanging one cryptoasset for another generally qualifies as a disposal for CGT purposes.
UAE
A genuine private investment swap generally does not create federal personal income tax, although business or regulatory considerations may apply.
EU
The treatment depends on the domestic law of the relevant member state.
Important: A transaction does not automatically become tax-free simply because it is completed without converting cryptocurrency into traditional money.
24. Is Staking or Mining Income Taxable?
Staking and mining may generate income or rewards.
The tax treatment depends on the jurisdiction.
| Jurisdiction | General Treatment |
|---|---|
| USA | Rewards may constitute taxable ordinary or business income |
| UK | Rewards may constitute taxable other income or trading income |
| UAE | Genuine personal activity requires classification; business activity may attract Corporate Tax |
| EU | Depends on each member state's income tax rules |
The receipt of staking rewards may be taxable in some jurisdictions even when the investor does not sell the received tokens.
Later disposal of those tokens can create an additional tax event.
Investors should record the market value at the relevant time of receipt where required by local law.
25. What About Cryptocurrency Gifts and Inheritance?
Gifting cryptocurrency can have different tax consequences across countries.
In the United States, a genuine gift may have different treatment from a sale, but gift-tax reporting and carryover basis rules can apply.
In the United Kingdom, gifting crypto to someone other than a qualifying spouse, civil partner or charity can create a chargeable capital gains disposal.
In the UAE, there is generally no federal personal income tax on a genuine private gift, but documentation and other legal obligations may still arise.
Within the EU, gifts and inheritance can be subject to different national tax regimes.
A taxpayer should not assume that sending cryptocurrency to another person's wallet is automatically tax-free.
26. Does Moving Cryptocurrency Between Wallets Create Tax?
Moving cryptocurrency between wallets owned by the same taxpayer is generally different from selling or exchanging the asset.
For example, transferring Bitcoin from an exchange account to a personally controlled wallet does not ordinarily represent a disposal if beneficial ownership remains unchanged.
However, the taxpayer must consider:
- Whether ownership genuinely remains the same.
- Whether crypto is exchanged during the transaction.
- Network fees paid using crypto.
- Custodial or beneficial ownership arrangements.
- Any additional DeFi transaction.
Wallet transfers should be properly documented to distinguish transfers from taxable sales.
27. Cryptocurrency Tax Calculation: Basic Example
Suppose an investor purchases cryptocurrency for $10,000 and sells it for $16,000.
| Description | Amount |
|---|---|
| Purchase Cost | $10,000 |
| Selling Proceeds | $16,000 |
| Illustrative Gain | $6,000 |
Capital Gain = Disposal Proceeds − Allowable Cost
The illustrative gain is $6,000.
Actual tax depends on the investor's tax residence and the applicable legal provisions.
For example:
- In the USA, the investor must consider short-term or long-term capital gains rules.
- In the UK, the investor must consider capital gains rates, the annual exemption and matching rules.
- In the UAE, genuine personal investment gains generally do not attract federal personal income tax.
- In the EU, the applicable national tax law determines liability.
There is no single international tax rate on the $6,000 gain.
28. Cryptocurrency Tax Record-Keeping Checklist
Investors should maintain reliable transaction records.
Important information includes:
- Purchase date.
- Purchase price.
- Amount of cryptocurrency acquired.
- Asset name and quantity.
- Exchange or wallet used.
- Transaction fees.
- Date of disposal.
- Selling proceeds.
- Value of assets received through swaps.
- Staking and mining rewards.
- Transfers between personal wallets.
- Relevant tax residency information.
- Exchange statements and transaction histories.
Where legally relevant, investors should preserve blockchain transaction references.
Maintaining records is important even when an exchange reports transactions to tax authorities.
29. Common Cryptocurrency Tax Mistakes in 2026
Investors should avoid:
- Assuming cryptocurrency is tax-free in every country.
- Treating the entire sale value as taxable profit.
- Failing to report crypto-to-crypto swaps where required.
- Ignoring staking or mining income.
- Assuming every UAE crypto business is tax-free.
- Applying one EU tax rate to all EU residents.
- Confusing DAC8 reporting with a new tax rate.
- Assuming tax is owed merely because crypto was transferred between personally owned wallets.
- Ignoring the UK annual CGT allowance.
- Applying a universal 15% US capital gains rate.
- Assuming no Form 1099-DA means no US reporting obligation.
- Failing to record transaction fees and acquisition costs.
- Using incorrect cryptocurrency cost-basis methods.
- Ignoring foreign tax residence and cross-border obligations.
- Failing to maintain transaction histories.
- Treating every token transfer as a genuine non-taxable gift.
30. Practical Tax Checklist for International Crypto Investors
Before preparing a cryptocurrency tax return:
- Determine your country of tax residence.
- Identify the applicable tax year.
- Review all exchange and wallet transactions.
- Separate purchases from taxable disposals.
- Identify crypto-to-crypto swaps.
- Calculate acquisition costs.
- Determine capital gains and losses.
- Identify staking and mining rewards.
- Review crypto-related business income.
- Check any applicable tax exemptions.
- Verify relevant capital gains rates.
- Review IRS Form 1099-DA where applicable.
- Review HMRC crypto reporting rules where applicable.
- Consider UAE Corporate Tax if conducting business.
- Check DAC8 and domestic EU reporting requirements.
- Retain all supporting records.
- File returns and pay taxes by the applicable deadlines.
31. Watch Tax With Naeem — Capital Gains and Income Tax Education
For general educational guidance on income tax return filing, capital gains, investment income and tax reporting, viewers can watch content from the Tax With Naeem YouTube channel.
Related Video: Income Tax Return Filing in Pakistan — Salary, Rental Income, Capital Gains and Dividends Explained
https://www.youtube.com/watch?v=VX88o1N1AfA
This is a Pakistan income tax tutorial, not a dedicated international cryptocurrency tax video.
It is included as supplementary education on income categories and return filing.
For cryptocurrency taxation in the USA, UK, UAE and EU, readers should use the official rules of the relevant tax authority.
32. Official Sources and References
United States — Internal Revenue Service
IRS Digital Assets Guide
https://www.irs.gov/filing/digital-assets
IRS Digital Asset Transaction FAQs
IRS Form 1099-DA Instructions
https://www.irs.gov/instructions/i1099da
United Kingdom — HM Revenue & Customs
HMRC: Tax When Selling Cryptoassets
https://www.gov.uk/guidance/check-if-you-need-to-pay-tax-when-you-sell-cryptoassets
HMRC: Tax When Receiving Cryptoassets
https://www.gov.uk/guidance/check-if-you-need-to-pay-tax-when-you-receive-cryptoassets
UK Cryptoasset Reporting Framework
https://www.gov.uk/guidance/reporting-cryptoasset-user-and-transaction-data
UK Capital Gains Tax Rates
https://www.gov.uk/guidance/capital-gains-tax-rates-and-allowances
United Arab Emirates
Federal Tax Authority — Corporate Tax for Natural Persons
Federal Tax Authority
UAE Government — Taxation
https://u.ae/en/information-and-services/finance-and-investment/taxation
European Union
European Commission — DAC8 Cryptoasset Reporting
European Commission — Cross-Border Taxation
OECD — International Tax Transparency
https://www.oecd.org/en/topics/international-standards-on-tax-transparency.html
Additional Educational Resources
AsaanTax.pk — International Taxation Guides
Tax With Naeem — Related Income Tax Tutorial
https://www.youtube.com/watch?v=VX88o1N1AfA
33. Conclusion: Which Countries Tax Cryptocurrency in 2026?
Cryptocurrency taxation varies significantly around the world.
In the United States, the IRS generally treats digital assets as property. Sales and exchanges may result in taxable capital gains, while staking, mining and other income-producing transactions can create income tax obligations.
In the United Kingdom, many personal cryptocurrency disposals fall within Capital Gains Tax rules, with 18% and 24% rates and a £3,000 annual exemption for the 2026–27 tax year.
In the UAE, genuine personal cryptocurrency investment gains are generally not subject to federal personal income tax, although businesses must consider Corporate Tax and other applicable regulations.
In the European Union, crypto taxation depends on each member state's domestic laws. The introduction of DAC8 from January 2026 strengthens international cryptoasset reporting without establishing one EU-wide crypto tax rate.
The most important principle is that cryptocurrency tax depends on tax residence, transaction type, gains, income classification and applicable local law—not simply the cryptocurrency being traded.
Investors should maintain accurate records, monitor tax authority guidance and ensure that taxable crypto transactions are correctly reported.
For more international tax guides covering cryptocurrency, the USA, UK, UAE, EU and Pakistan, visit AsaanTax.pk.
Editorial Note: This article reflects official guidance reviewed as of November 10, 2026. Tax rates, exemptions, reporting requirements and the treatment of digital assets may vary across countries and taxpayer categories.
Disclaimer: This content is for general educational purposes and is not individualized tax, legal or investment advice. Cryptocurrency taxation can be complex, particularly where transactions involve multiple jurisdictions, staking, DeFi or business activities. Readers should consult the relevant tax authority or a qualified tax professional before filing.