Oman Introduces Personal Income Tax From 2028: 5% Above OMR 42,000 — What Expats Must Know
Published: November 11, 2026
Country: Sultanate of Oman
Law: Royal Decree No. 56/2025
Effective Date: January 1, 2028
Tax Authority: Oman Tax Authority
Tax Rate: 5%
Annual Gross Income Threshold: OMR 42,000
Oman is preparing for one of the most significant changes to personal taxation in the Gulf region.
For decades, Oman has attracted international workers, professionals, investors and expatriate families partly because ordinary employment salaries have not been subject to personal income tax.
However, this will change for qualifying higher-income individuals from January 1, 2028.
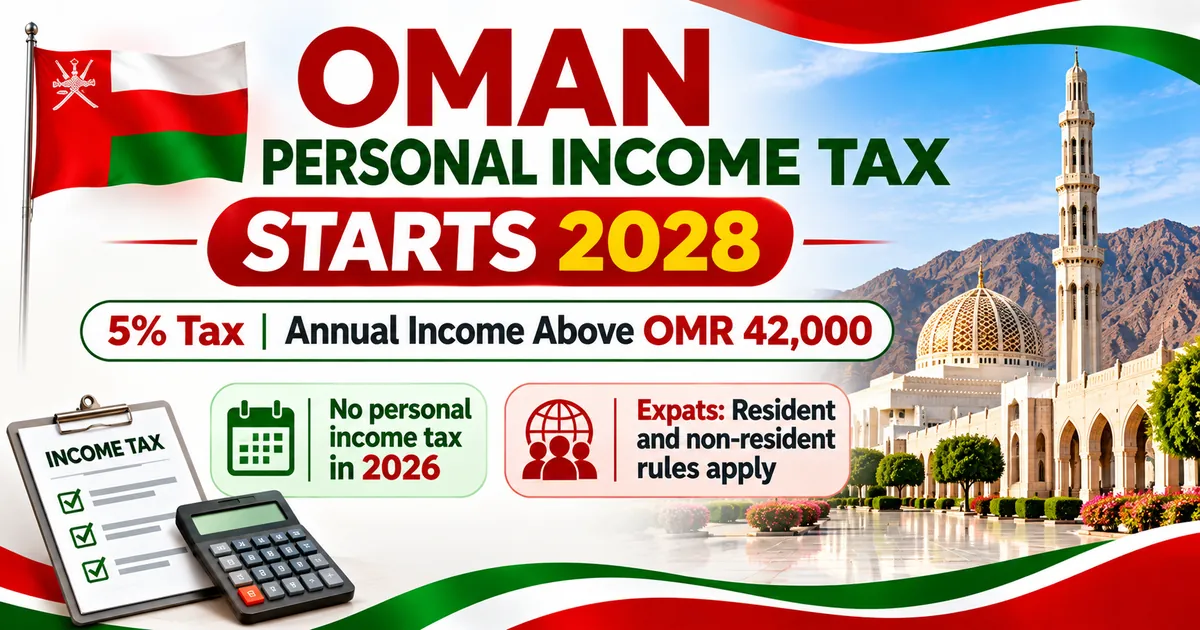
Under Royal Decree No. 56/2025, Oman introduced a Personal Income Tax Law imposing a 5% tax on taxable income where the individual's relevant total annual income exceeds OMR 42,000.
The legislation was issued on June 22, 2025, and published in the Official Gazette on June 30, 2025.
Important: Personal Income Tax does not apply to ordinary employment salaries during 2026 or 2027 under this new law.
The law is scheduled to take effect from January 1, 2028.
It will cover eligible Omani nationals and expatriates, with different rules for residents and non-residents.
This guide explains the new tax, the OMR 42,000 threshold, tax residency, foreign income, salary allowances, deductions, tax returns, employer obligations and what Pakistani and other expatriate workers should prepare before implementation.
1. What Is Oman's New Personal Income Tax?
Personal Income Tax (PIT) is a tax imposed directly on the taxable income of individuals.
Oman's new regime was introduced through Royal Decree No. 56/2025.
The law contains 76 articles across 16 chapters and provides a framework for taxing specified categories of individual income.
The Oman Tax Authority states that the law supports Oman Vision 2040 and the government's wider revenue-diversification strategy.
It is designed to focus primarily on higher-income individuals.
According to the Tax Authority's analysis, approximately 99% of the population is not expected to become subject to the tax.
Key Provisions
| Requirement | Rule |
|---|---|
| Law | Royal Decree No. 56/2025 |
| Effective Date | January 1, 2028 |
| Personal Income Tax Rate | 5% |
| Annual Gross Income Threshold | More than OMR 42,000 |
| Taxpayer Category | Qualifying individuals |
| Expatriates | Included where relevant conditions apply |
| Tax Residence | Generally more than 183 days in Oman during the year |
| Resident Income Scope | Relevant worldwide income |
| Non-Resident Income Scope | Relevant Oman-source income |
| Tax Authority | Oman Tax Authority |
The applicable tax is determined after considering the statutory threshold, exemptions, deductions and relevant taxable-income calculations.
2. Is Personal Income Tax Already Applicable in Oman in 2026?
No.
Oman's new Personal Income Tax Law does not take effect until January 1, 2028.
Ordinary employment salaries remain outside the new PIT charge in 2026 and 2027.
Implementation Timeline
| Year | Personal Income Tax Position |
|---|---|
| 2025 | Law issued under Royal Decree No. 56/2025 |
| 2026 | New PIT not yet applicable |
| 2027 | Preparatory period before implementation |
| January 1, 2028 | New PIT law takes effect |
| 2029 | First normal annual return cycle for income earned in 2028 |
The law already exists, but the commencement date is in the future.
Employers and individuals should prepare in advance without incorrectly deducting the new personal income tax from 2026 salaries.
3. Who Will Pay Personal Income Tax in Oman?
The law applies to qualifying natural persons whose relevant annual income exceeds the specified threshold.
The following groups may be affected:
- Higher-income employees.
- Senior executives.
- Company directors.
- Independent professionals.
- Consultants.
- Freelancers.
- Individuals earning rental income.
- Persons receiving relevant investment income.
- Individuals receiving taxable overseas income.
- Certain non-residents with Oman-source income.
The actual tax calculation depends on whether the individual is resident or non-resident and on the income categories covered by the law.
Important for Expatriates
The new law is not restricted to Omani citizens.
Foreign professionals living or working in Oman may also be subject to its provisions.
A Pakistani, Indian, British or other expatriate cannot claim exemption solely on the basis of nationality.
4. What Is the OMR 42,000 Annual Income Threshold?
The Oman Tax Authority has established an annual gross income threshold of OMR 42,000.
An individual whose relevant annual total income does not exceed the threshold generally will not be subject to the new PIT.
Where the threshold is exceeded, taxable income must be calculated using the relevant provisions.
Annual and Monthly Threshold
| Income Period | Equivalent Amount |
|---|---|
| Annual | OMR 42,000 |
| Monthly Average | OMR 3,500 |
| Quarterly Average | OMR 10,500 |
OMR 3,500 per month is a convenient comparison, not a separate statutory monthly exemption.
The law is based on annual income.
Bonuses, allowances and other relevant receipts may cause annual income to exceed OMR 42,000 even when the regular monthly salary is lower than OMR 3,500.
5. Does Oman Charge 5% on the Entire Salary?
No.
The new PIT is not simply a flat 5% charge on an individual's entire annual salary after crossing the threshold.
The law distinguishes between:
Total Income: Relevant gross income and benefits.
Net Income: Income above the OMR 42,000 threshold.
Taxable Income: Net income after applicable exemptions, costs, losses and treaty-related adjustments.
The general calculation can be expressed as:
Taxable Income = Amount Above the Threshold − Eligible Adjustments
Personal Income Tax = 5% × Taxable Income
This is a simplified formula.
The actual calculation must follow the statutory rules and the relevant implementation guidance.
6. Oman Income Tax Calculation Examples
The following examples illustrate the basic threshold and 5% rate.
They assume a qualifying individual with ordinary income and no additional deductions or exemptions beyond the threshold.
Example 1: Annual Income of OMR 30,000
Annual income: OMR 30,000.
Threshold: OMR 42,000.
The individual does not exceed the threshold.
Illustrative PIT: OMR 0.
Example 2: Annual Income of OMR 42,000
Annual income: OMR 42,000.
The threshold is not exceeded.
Illustrative PIT: OMR 0.
Example 3: Annual Income of OMR 48,000
Annual income: OMR 48,000.
Amount exceeding threshold:
OMR 48,000 − OMR 42,000 = OMR 6,000.
Tax at 5%:
OMR 6,000 × 5% = OMR 300.
Illustrative PIT: OMR 300.
Example 4: Annual Income of OMR 60,000
Annual income: OMR 60,000.
Amount exceeding threshold:
OMR 60,000 − OMR 42,000 = OMR 18,000.
Tax at 5%:
OMR 18,000 × 5% = OMR 900.
Illustrative PIT: OMR 900.
Example 5: Annual Income of OMR 100,000
Annual income: OMR 100,000.
Amount exceeding threshold:
OMR 100,000 − OMR 42,000 = OMR 58,000.
Tax at 5%:
OMR 58,000 × 5% = OMR 2,900.
Illustrative PIT: OMR 2,900.
Quick Tax Calculation Table
| Annual Relevant Income | Illustrative PIT |
|---|---|
| OMR 24,000 | OMR 0 |
| OMR 36,000 | OMR 0 |
| OMR 42,000 | OMR 0 |
| OMR 45,000 | OMR 150 |
| OMR 48,000 | OMR 300 |
| OMR 60,000 | OMR 900 |
| OMR 75,000 | OMR 1,650 |
| OMR 100,000 | OMR 2,900 |
These are educational illustrations, not assessments of actual tax liability. Eligible deductions, exemptions and the classification of income can alter the result.
7. Will All Expatriates Pay Income Tax From 2028?
No.
The Oman Tax Authority expects the majority of people living in Oman to remain outside the charge because of the relatively high annual income threshold.
An expatriate employee earning OMR 1,500 or OMR 2,000 per month, without other relevant income, would ordinarily remain below OMR 42,000 annually.
However, individuals with multiple sources of income must examine their combined relevant receipts.
Example: Salary Plus Rental Income
Assume an expatriate earns:
- Annual salary: OMR 36,000.
- Annual relevant rental income: OMR 12,000.
Combined annual income:
OMR 48,000.
The person's income exceeds the OMR 42,000 threshold.
They must then determine the actual taxable amount using the relevant rules.
Important: Checking salary alone is not sufficient where the person also earns other income covered by the law.
8. Oman Tax Residency: The 183-Day Rule
Tax residency is central to the new law.
The Oman Tax Authority's published guidance uses a presence test of more than 183 days during the relevant tax year.
The days can be consecutive or intermittent.
Tax Resident
An individual meeting the residence test is generally subject to the relevant rules concerning worldwide income.
Non-Resident
An individual who does not meet the residence test is generally subject to the applicable rules concerning Oman-source income.
Example
A professional spends most of the year living and working in Muscat.
If their presence satisfies Oman's statutory residency test, they may be treated as a resident for PIT purposes.
The person's tax obligations will then be determined according to the resident-income provisions.
Nationality and possession of an Oman residence permit are not, by themselves, sufficient substitutes for the statutory residence calculation.
9. Will Foreign Income Be Taxable in Oman?
For a qualifying Oman tax resident, the new law can cover relevant income earned both inside and outside Oman.
This is an important change for expatriates who own overseas investments or receive foreign income.
Potentially relevant income can include:
- Foreign employment income.
- Overseas property income.
- Foreign bank interest.
- Certain dividends.
- Investment-related income.
- Other taxable overseas receipts.
However, specific exemptions, deductions, transitional relief and treaty provisions may affect the final calculation.
Example: Pakistani Expatriate
A Pakistani professional resides in Oman and earns:
- Oman employment income.
- Rental income from a property in Pakistan.
- Interest from an overseas account.
The person should determine whether their annual total income exceeds the threshold and which receipts are included under the new law.
The existence of foreign income does not automatically mean every amount will be taxed at 5%.
10. What About Non-Residents Earning Income From Oman?
The law also includes provisions relating to non-resident individuals.
A non-resident's relevant tax base generally concerns income arising from Oman rather than their worldwide income.
Example
An international consultant lives outside Oman but provides relevant taxable services connected with Oman.
The consultant may need to review the non-resident provisions, including applicable withholding obligations and any tax treaty relief.
The amount and nature of the payment can affect the tax treatment.
Businesses should not automatically apply the resident worldwide-income rules to a non-resident.
11. Which Income Sources Can Be Included?
The Personal Income Tax framework covers multiple categories of relevant individual income.
Examples include:
| Income Category | Potential PIT Relevance |
|---|---|
| Salary and wages | Included under relevant provisions |
| Employment bonuses | May be included |
| Cash and in-kind benefits | May be included |
| Self-employment income | Included under relevant conditions |
| Property rental income | Potentially taxable |
| Royalties | Potentially taxable |
| Interest and dividends | Subject to relevant provisions |
| Certain capital gains | Subject to specific rules |
| Pensions | Relevant rules may apply |
| Director and council remuneration | Potentially included |
The final assessment depends on the applicable exemptions and definitions.
Different categories may have different allowable costs or deductions.
12. Are Housing and Education Expenses Deductible?
The Oman Tax Authority states that the new PIT regime includes deductions and exemptions designed to account for personal and family circumstances.
Potentially relevant categories include:
- Housing finance costs.
- Education expenses.
- Healthcare expenses.
- Qualifying charitable contributions.
- Zakat.
- Certain donations and endowments.
- Other specifically permitted expenditures.
The exact deductible amount, documentation requirements and eligibility restrictions are determined by the law and applicable regulations.
Important
An employee should not assume that every rent payment, medical bill or educational expense is fully deductible.
Similarly, receiving a housing allowance does not automatically make the entire allowance exempt.
Each item must be evaluated under the relevant legal provisions.
13. Are End-of-Service Benefits and Pensions Taxable?
The legislation identifies multiple types of individual income, including certain pension and employment-related receipts.
However, specific exemptions may apply to qualifying benefits.
Employment gratuities, end-of-service payments and pension arrangements should be reviewed using their particular statutory treatment.
The Oman Tax Authority's published FAQs also confirm that retirement pensions are among the income sources relevant to the PIT calculation.
Therefore, a taxpayer should not automatically assume that every pension or retirement payment is fully taxable or fully exempt.
The correct result depends on the detailed provisions.
14. Is Residential Rental Income Taxable?
Rental income is an important category under the new PIT regime.
The Oman Tax Authority has clarified that income received from residential rental property can fall within the PIT system.
This is a separate matter from the VAT exemption for certain residential property transactions.
Example
An individual earns rental income from a residential building.
If the individual's relevant annual income exceeds the OMR 42,000 threshold, they may need to include qualifying rental receipts in the PIT calculation.
The landlord should then determine eligible deductions and expenses.
Important: A residential rental transaction can be treated as exempt from VAT while the resulting rental income remains relevant for Personal Income Tax.
VAT and PIT are separate taxes.
15. Will Freelancers and Consultants Pay Oman Personal Income Tax?
Independent professionals can also fall within the new law.
Examples include:
- Software developers.
- Designers.
- Photographers.
- Consultants.
- Freelance writers.
- Digital marketing specialists.
- Other self-employed professionals.
The Oman Tax Authority's FAQ provides an example of a photographer earning OMR 50,000 annually who falls within the PIT system even without a commercial registration.
Self-Employment Expenses
According to the Tax Authority's current guidance, qualifying self-employed persons may have an option between:
- A deduction equal to 15% of relevant gross self-employment income; or
- Actual qualifying expenses supported by records.
The applicable method and calculation must follow the regulations.
A freelancer should maintain invoices, receipts, bank statements and documentation of relevant costs.
16. Will Employers Deduct the New Tax From Salaries?
Yes, employer withholding is part of the intended compliance framework.
The Oman Tax Authority has confirmed that covered employers in government, private and relevant foreign-business sectors will have obligations to withhold and remit tax under the new regime.
What Employers Should Prepare
- Review employee salary and benefit structures.
- Identify employees potentially exceeding the annual income threshold.
- Update payroll records and systems.
- Verify employee tax-residency information.
- Track bonuses and relevant benefits.
- Review statutory deductions and exemptions.
- Establish tax withholding procedures.
- Maintain proper documentation.
- Monitor Oman Tax Authority implementation guidance.
- Inform employees about the changes before 2028.
The final withholding processes and payroll requirements should follow official instructions.
17. Will Individuals Need to File a Personal Income Tax Return?
Yes, where the relevant statutory filing conditions are met.
According to the Oman Tax Authority, residents whose relevant annual total income exceeds OMR 42,000 are required to submit a tax return.
The legislation provides for electronic tax returns.
General Filing Deadline
The law generally provides a deadline of six months after the end of the relevant tax year.
For a calendar-year taxpayer reporting 2028 income, this ordinarily points to a filing deadline in 2029.
The actual deadline and filing procedures should be confirmed against the official implementation guidance.
Employer Filing on Behalf of an Employee
The law also contains provisions allowing an employer to submit a return on behalf of an employee in qualifying circumstances, subject to the applicable conditions and employee request.
Individuals should not assume that employer withholding always eliminates every personal filing responsibility.
18. What Records Should Expatriates Maintain?
Individuals expecting to become subject to PIT should prepare documentation well before 2028.
Useful records can include:
- Employment contracts.
- Salary certificates.
- Monthly payslips.
- Bonus and incentive records.
- Housing and education benefit details.
- Foreign bank statements.
- Rental income records.
- Business income records.
- Property ownership documentation.
- Eligible expense receipts.
- Charitable contribution records.
- Foreign tax payment certificates.
- Travel and residency records.
- Other documents supporting exemptions and deductions.
Maintaining accurate records is important where a person earns income from multiple countries.
19. Can Tax Paid Abroad Be Credited in Oman?
The new PIT system recognises relevant foreign-tax considerations and international agreements.
The Oman Tax Authority's guidance indicates that eligible foreign tax must relate to income that is subject to the Oman PIT rules.
The availability of relief depends on the nature of the foreign income, the foreign tax paid and the applicable statutory provisions.
Example
An Oman tax resident earns relevant taxable income from another country and pays foreign tax on that income.
The individual may need to examine whether relief is available under Oman's rules or an applicable treaty.
Foreign tax paid on unrelated or excluded income should not automatically be deducted from an Oman tax liability.
20. Do Pakistani Expats Need to Pay Tax in Both Pakistan and Oman?
Pakistani professionals working in Oman should assess their tax residence independently under each country's laws.
Important factors include:
- Number of days spent in Pakistan.
- Number of days spent in Oman.
- Source of employment income.
- Foreign rental and investment income.
- Pakistani tax residency.
- The relevant Pakistan–Oman double taxation arrangements.
- Available foreign tax credits.
- Wealth statement or other reporting requirements.
Example
A Pakistani professional resides in Oman and earns a high salary together with Pakistani rental income.
The employee may need to consider the Oman PIT framework from 2028.
The person's Pakistani income tax position depends on Pakistani residency and income-source rules.
The existence of an Oman work visa or bank account does not automatically resolve Pakistani tax obligations.
21. Oman Personal Income Tax vs Corporate Income Tax
It is important to distinguish the new personal tax from Oman's existing company taxation system.
| Tax Type | General Position |
|---|---|
| Personal Income Tax | 5% on relevant taxable income from 2028 |
| Standard Corporate Income Tax | Generally 15% |
| Certain Qualifying Small Enterprise Income | Special 3% treatment may apply |
| Value Added Tax | Standard rate of 5% |
| Excise Tax | Applies to specified goods |
The new PIT is a tax on individuals, not a replacement for corporate income tax.
An incorporated business and its owner may have different tax obligations.
22. Does Oman Have VAT in 2026?
Yes.
Oman introduced VAT in April 2021.
The standard VAT rate is generally 5%.
VAT applies to relevant taxable supplies of goods and services, subject to zero-rating and exemptions.
Example
A standard-rated sale has a pre-tax value of OMR 1,000.
VAT at 5%:
OMR 50.
Total invoice:
OMR 1,050.
VAT and personal income tax are separate obligations.
A salaried employee may pay VAT on purchases during 2026 even though the new personal income tax is not yet in force.
23. How Is Oman Different From Other GCC Countries?
The Gulf Cooperation Council countries have historically avoided general personal income tax on employment salaries.
Oman's enacted PIT law represents a significant regional development.
Comparison
| Country | Ordinary Salary Income Tax in 2026 |
|---|---|
| UAE | None |
| Saudi Arabia | None |
| Qatar | None |
| Oman | None — 5% PIT starts in 2028 for qualifying individuals |
| Kuwait | None |
| Bahrain | None |
Oman is the first GCC country to enact this general high-income personal tax framework.
However, the absence of general salary tax in other countries does not mean business income, VAT or other obligations are exempt.
24. Why Is Oman Introducing Personal Income Tax?
The government has identified several policy objectives behind the law.
These include:
Revenue Diversification
Reducing dependence on revenue generated from oil and gas.
Oman Vision 2040
Supporting economic diversification and long-term fiscal objectives.
Social Protection
Providing additional resources for public services and social protection.
Distribution of the Tax Burden
Concentrating the new tax on relatively higher-income individuals.
Modern Tax Administration
Establishing improved reporting and compliance systems for individuals and employers.
The high OMR 42,000 threshold is intended to keep most residents outside the PIT charge.
25. How Should Expatriates Prepare Before 2028?
Individuals working in Oman should take several practical steps before the new law begins.
Step 1: Review Annual Income
Calculate all relevant income sources rather than salary alone.
Step 2: Identify Tax Residency
Review actual days spent in Oman and the relevant residence rules.
Step 3: Check Employment Benefits
Confirm how cash and non-cash benefits are treated.
Step 4: Review Overseas Income
Identify foreign rental, interest, dividend and other relevant income.
Step 5: Maintain Expense Records
Keep documentation for potentially eligible deductions.
Step 6: Discuss Payroll With Employers
Confirm whether the employer is preparing for withholding obligations.
Step 7: Monitor Official Regulations
Review the Oman Tax Authority's updated guidance before implementation.
Step 8: Consider International Tax Relief
Individuals with income from more than one country should consider treaty and foreign tax credit rules.
Step 9: Plan Cash Flow
Estimate any future tax liability using the correct statutory taxable-income calculation.
Step 10: Seek Professional Advice Where Necessary
Complex international income and high-value transactions should be reviewed by a qualified professional.
26. Common Oman Personal Income Tax Mistakes
Avoid these common errors:
- Assuming PIT already applies in 2026.
- Applying the 5% rate to every employee's entire salary.
- Treating OMR 42,000 as a monthly threshold.
- Assuming all expatriates are exempt.
- Checking salary without considering other relevant income.
- Ignoring Oman's tax-residency test.
- Assuming worldwide income is irrelevant to residents.
- Treating VAT exemptions as PIT exemptions.
- Claiming unsupported deductions.
- Confusing Personal Income Tax with Corporate Income Tax.
- Assuming withholding removes every filing obligation.
- Ignoring foreign income and tax treaty provisions.
- Failing to keep employment and business records.
- Treating every foreign bank transfer as taxable income.
- Using unverified social media information instead of the Tax Authority's current guidance.
27. Oman Personal Income Tax Preparation Checklist
Before January 2028, verify the following:
- The effective date of January 1, 2028.
- Annual relevant gross income.
- Whether income exceeds OMR 42,000.
- Tax residency status.
- Employment and bonus income.
- Non-cash employment benefits.
- Freelance or business receipts.
- Rental income.
- Interest and investment income.
- Overseas income.
- Relevant statutory exemptions.
- Eligible deductions and expenses.
- Employer withholding arrangements.
- Record-keeping requirements.
- Foreign taxes and treaty relief.
- Electronic filing procedures.
- Applicable filing and payment deadlines.
- Latest Oman Tax Authority notices.
28. Watch Tax With Naeem — Related Income Tax Education
For general educational guidance on income taxation, salary income, rental income, capital gains, dividends and tax return preparation, watch the following video from Tax With Naeem.
Related Video: Income Tax Return Filing in Pakistan — Salary, Rental Income, Capital Gains and Dividends Explained
https://www.youtube.com/watch?v=VX88o1N1AfA
This video was published by Tax With Naeem on October 2, 2025.
It explains Pakistan's income tax system and is included as supplementary educational material.
Important: This is not an Oman Personal Income Tax filing tutorial.
For the Oman PIT regime, expatriates should rely on the Oman Tax Authority and the applicable Omani legislation.
29. Official Oman Tax Sources and References
1. Oman Tax Authority — Issuance of Personal Income Tax Law
https://tms.taxoman.gov.om/portal/w/issuance-of-personal-income-tax-pit-law
2. Oman Tax Authority — Personal Income Tax FAQs
https://tms.taxoman.gov.om/portal/personal-income-tax-faqs
3. Oman Tax Authority — Personal Income Tax Law and Regulations
https://tms.taxoman.gov.om/portal/personal-income-tax-law-and-regulation
4. Royal Decree No. 56/2025 — Personal Income Tax Law
https://decree.om/2025/rd20250056/
5. Oman Tax Authority — Official Tax Portal
https://tms.taxoman.gov.om/portal/
6. PwC — Oman Personal Income Tax Overview
https://taxsummaries.pwc.com/oman/individual/taxes-on-personal-income
7. AsaanTax.pk — International Taxation Guides
8. Tax With Naeem — Related Income Tax Video
https://www.youtube.com/watch?v=VX88o1N1AfA
30. Conclusion: What Will Oman's 5% Income Tax Mean for Expats?
Oman's new Personal Income Tax Law represents a major change in the Gulf's taxation landscape.
The law was enacted in June 2025 but does not come into force until January 1, 2028.
It establishes a 5% rate on relevant taxable income for qualifying individuals whose annual gross income exceeds OMR 42,000.
The rules cover eligible expatriates and Omani nationals, with important distinctions between residents and non-residents.
Employees earning below the threshold without other relevant income generally will not become subject to this tax.
However, higher-income employees, business professionals, property owners and individuals with overseas income should prepare carefully.
The actual tax is calculated after applying the statutory threshold and relevant deductions and exemptions, rather than charging 5% on the entire salary.
The most important message for expatriates is that Oman remains free of general personal salary income tax in 2026 and 2027, but qualifying higher-income individuals must prepare for the new tax regime beginning in 2028.
For more guides on Oman taxation, Gulf employment income, UAE Corporate Tax, Saudi Arabia VAT and international taxation, visit:
AsaanTax.pk: https://www.asaantax.pk/
Editorial Note: This article reflects the Oman Personal Income Tax Law and Oman Tax Authority guidance reviewed as of November 11, 2026, including the official FAQ update dated November 5, 2026.
Disclaimer: This article provides general educational information and does not constitute individualized Omani or international tax advice. Actual obligations depend on tax residence, the type and source of income, eligible exemptions, deductions, employer withholding and applicable regulations. Readers should consult the Oman Tax Authority or a qualified professional for specific circumstances.