UK Non-Dom Rules Are Gone: The 4-Year Foreign Income and Gains (FIG) Regime Explained
Published: 10 November 2026
Country: United Kingdom
Applicable Tax Year: 2026–27 (6 April 2026 to 5 April 2027)
Tax Authority: HM Revenue & Customs (HMRC)
Major Reform Effective: 6 April 2025
The United Kingdom has fundamentally changed how foreign income and capital gains are taxed for individuals who move to the country.
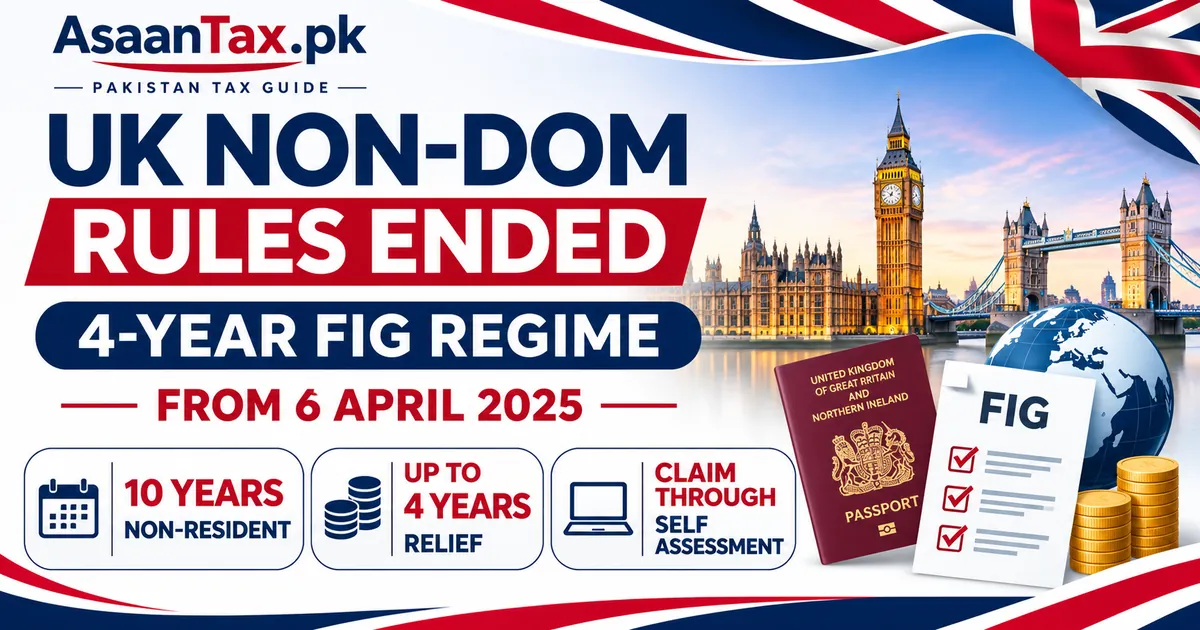
The traditional UK non-domiciled, or "non-dom", remittance-basis tax system was abolished from 6 April 2025 and replaced by the residence-based four-year Foreign Income and Gains (FIG) regime.
Under the new system, eligible individuals who become UK tax residents after at least 10 consecutive tax years of non-UK residence may claim relief from UK tax on qualifying foreign income and gains arising during their first four tax years of UK residence.
This change is especially important for overseas Pakistanis moving to Britain, international entrepreneurs, investors, landlords, returning British expatriates and individuals with overseas investments.
However, the FIG regime is not an automatic tax exemption. Eligibility must be established, a claim must be made through Self Assessment, and valuable personal tax allowances can be lost.
This complete guide explains the 2026–27 FIG rules, eligibility criteria, examples, foreign income exemptions, Self Assessment procedures, transitional provisions and common mistakes.
1. What Happened to the UK's Non-Dom Tax Rules?
Before 6 April 2025, certain UK residents who were not domiciled in the UK could use the remittance basis of taxation.
Broadly, this allowed qualifying individuals to pay UK tax on certain overseas income and capital gains primarily when those amounts were brought into the UK.
The detailed rules depended on the individual's residence history, domicile and applicable elections.
From 6 April 2025, this remittance-basis system was abolished for new foreign income and gains.
The UK introduced a new system based on tax residence rather than domicile.
The central relief is the four-year FIG regime for qualifying new UK residents.
Important: The abolition of the old rules does not mean every person previously treated as non-domiciled automatically qualifies for FIG relief.
2. What Is the Four-Year Foreign Income and Gains Regime?
The FIG regime allows qualifying new UK residents to claim 100% UK tax relief on specified foreign income and foreign capital gains arising during their qualifying period.
An eligible person generally must:
- Be UK tax resident under the Statutory Residence Test.
- Have been non-UK tax resident for at least 10 consecutive tax years before the relevant arrival.
- Be within the first four tax years of UK residence following that non-resident period.
- Meet all other applicable conditions.
- Make a valid claim for the income or gains concerned.
Main Features of FIG Relief
| Feature | General Rule |
|---|---|
| Start Date | 6 April 2025 |
| Maximum Qualifying Period | Four consecutive tax years |
| Previous Non-Residence Requirement | At least 10 consecutive UK tax years |
| Qualifying Foreign Income Relief | Up to 100% |
| Qualifying Foreign Gains Relief | Up to 100% |
| Automatic Exemption | No — claim required |
| Claim Method | Self Assessment |
| UK-Source Income | Generally taxable under normal UK rules |
| Personal Allowance After Claim | Generally lost |
| Ability to Bring Relieved FIG to UK | No additional UK remittance tax on qualifying relieved amounts |
The regime applies only to qualifying categories of income and gains.
Not every international transaction is eligible.
3. Who Qualifies for the FIG Regime in 2026–27?
The main eligibility requirement is UK tax residence within the first four-year period following at least 10 consecutive tax years of non-UK residence.
Nationality does not determine eligibility.
For example, a Pakistani citizen, British citizen or another national can potentially qualify if the residence and other statutory conditions are met.
Example 1: Pakistani Professional Moving to London
Suppose a Pakistani professional was non-UK tax resident for 10 consecutive tax years and first became UK tax resident in 2026–27.
Their potential qualifying years are:
| Tax Year | Potential FIG Position |
|---|---|
| 2026–27 | Year 1 |
| 2027–28 | Year 2 |
| 2028–29 | Year 3 |
| 2029–30 | Year 4 |
| 2030–31 | Outside initial four-year period |
A valid FIG claim could provide relief on qualifying foreign income or gains arising during those four years.
UK salary and other UK-source taxable income remain subject to the applicable rules.
Example 2: Individual Who Moved Earlier
Suppose a person first became UK tax resident in 2023–24 after satisfying the 10-year non-residence condition.
Their four-year period is:
- 2023–24: Year 1.
- 2024–25: Year 2.
- 2025–26: Year 3.
- 2026–27: Year 4.
Because FIG began on 6 April 2025, that individual may potentially claim for 2025–26 and 2026–27.
The regime does not retrospectively provide FIG relief for 2023–24 and 2024–25.
4. How Does the 10-Year Non-Residence Test Work?
The taxpayer must establish at least 10 consecutive UK tax years of non-residence before becoming UK resident.
UK tax residence is determined using the Statutory Residence Test (SRT).
The SRT considers relevant factors such as:
- Days spent in the United Kingdom.
- UK accommodation.
- Family ties.
- Work performed in the UK.
- Previous UK residence.
- Other statutory connections.
Simply holding a foreign passport or maintaining an overseas address is insufficient.
A taxpayer should prepare a detailed residence history before claiming the FIG regime.
Example
An individual lived outside the UK and was non-UK resident for the 10 tax years immediately preceding 2026–27.
If that person becomes UK tax resident in 2026–27, they may satisfy the residence-history requirement.
However, any UK tax residence during the required 10-year period could affect eligibility.
5. Which Foreign Income Qualifies for FIG Relief?
HMRC identifies several categories of potentially qualifying foreign income.
These include:
- Interest received from qualifying foreign bank accounts.
- Dividends from non-UK resident companies.
- Profits from an overseas property business.
- Profits from a trade carried on wholly outside the UK.
- Certain foreign pension income.
- Other specified qualifying foreign income.
Eligibility depends on the detailed source and statutory classification.
Example: Pakistani Rental Property
Suppose an eligible individual becomes UK resident and owns rental property in Pakistan.
The person receives £15,000 equivalent in qualifying foreign property income during the year.
If all relevant FIG conditions are satisfied and a valid claim is made, the qualifying foreign income may receive UK relief.
The property income may still have tax consequences in Pakistan.
FIG relief does not automatically eliminate obligations under another country's tax laws.
6. Are Foreign Capital Gains Exempt Under FIG?
Qualifying foreign capital gains arising during an eligible FIG period may receive UK Capital Gains Tax relief when validly claimed.
For example, a qualifying new UK resident may sell overseas investment assets and realize a foreign capital gain.
The taxpayer must determine whether the gain qualifies under the FIG rules.
Example
Assume an eligible taxpayer realizes a £40,000 qualifying foreign capital gain during 2026–27.
If a valid foreign-gain claim covers that gain, the person may receive UK relief on it.
However, the claimant must consider the loss of the Capital Gains Tax annual exempt amount and other allowances.
The result should be compared with normal UK taxation before deciding whether to claim.
7. Can FIG-Relieved Money Be Brought Into the UK?
Yes.
A significant difference between the new FIG regime and the old remittance basis is the treatment of qualifying relieved amounts.
Where foreign income or gains arise during an eligible tax year and receive FIG relief under a valid claim, bringing those relieved funds into the UK does not create an additional UK remittance tax charge merely because they are transferred.
Example
A qualifying resident receives foreign bank interest that is validly relieved under FIG.
The person later transfers the relieved money from an overseas account into a UK bank account.
That transfer does not itself create an additional UK remittance tax liability on the relieved income.
Important: Different rules may apply to foreign income and gains arising before 6 April 2025 under the former remittance-basis system.
Those older amounts must be reviewed separately.
8. Does Foreign Salary Qualify for FIG Relief?
Not under the ordinary FIG foreign-income claim.
HMRC states that foreign employment earnings are not qualifying foreign income for the general FIG relief.
However, qualifying employees may be eligible for a separate Overseas Workday Relief (OWR) regime.
OWR applies to specified employment income attributable to duties performed outside the UK, subject to detailed conditions.
Overseas Workday Relief Limit
From 6 April 2025, the ordinary annual financial limit is the lower of:
- 30% of relevant qualifying employment income; or
- £300,000.
The treatment of employees who were already using the earlier Overseas Workday Relief regime may involve transitional rules.
A person should not claim the ordinary FIG foreign-income exemption on UK employment earnings merely because those earnings were paid into an overseas bank account.
9. What Happens to the UK Personal Allowance if FIG Is Claimed?
This is one of the most important costs of making a FIG claim.
A person claiming FIG relief generally loses entitlement to important personal tax allowances for the relevant tax year.
These include:
- Income Tax Personal Allowance.
- Capital Gains Tax annual exempt amount.
- Blind Person's Allowance.
- Certain married-couple and transferable tax allowances.
- Other specified reliefs.
For 2026–27, the standard UK Personal Allowance is £12,570.
Therefore, a FIG claim can increase UK tax payable on income that does not qualify for FIG relief.
Example
An eligible individual has:
- UK salary: £30,000.
- Qualifying overseas investment income: £50,000.
The person may benefit from FIG relief on the qualifying foreign income.
However, the claim generally removes their UK Personal Allowance.
Before making a claim, the taxpayer should compare the foreign-income tax saved with any additional UK tax resulting from lost allowances.
Important: Making even a limited FIG claim can result in the loss of the relevant allowances for that year.
10. Must FIG Relief Be Claimed Every Year?
Yes. A taxpayer must make a claim for each tax year in which they want FIG relief.
The relief is not automatically applied for four consecutive tax years.
A qualifying person may choose to claim in one year and not another.
However, an unused year cannot be added to the end of the original four-year period.
Example
A taxpayer becomes UK resident in 2025–26.
The four-year period runs from 2025–26 to 2028–29.
If the taxpayer does not claim relief in 2026–27, they do not receive an additional fifth year in 2029–30.
The four-year clock still runs.
11. What If Someone Temporarily Leaves the UK?
A person may temporarily become non-UK resident during their four-year FIG period.
They cannot claim FIG relief for a tax year in which they are not UK tax resident.
However, they may be eligible to claim in later remaining qualifying years if they return to UK residence within the original four-year period.
The unused non-resident year does not extend the period.
The Statutory Residence Test must be applied independently for each tax year.
12. How to Claim the FIG Regime Through HMRC Self Assessment
FIG relief must be claimed through the individual's Self Assessment return.
HMRC requires qualifying foreign income and gains to be identified on a source-by-source basis.
Step 1: Establish UK Tax Residence
Determine the taxpayer's residence status using the Statutory Residence Test.
Step 2: Verify the Previous 10 Years
Review the relevant non-residence history and evidence.
Step 3: Identify the Four-Year Period
Determine the first UK-resident tax year and the remaining eligible years.
Step 4: Classify Foreign Income and Gains
Separate qualifying income from disqualified income, including employment income that requires different treatment.
Step 5: Calculate the Tax Consequences
Compare FIG relief with normal tax treatment, including the loss of allowances.
Step 6: Prepare Self Assessment
Complete the relevant return and supplementary pages, including the residence and FIG information.
Step 7: Identify Each Claimed Source
Report relevant foreign income or gains individually according to HMRC's requirements.
Step 8: Submit the Claim
Submit the completed return within the applicable claim time limit.
Step 9: Maintain Supporting Records
Retain residence evidence, overseas income statements, transaction records and calculations.
Step 10: Review Future Years
Reassess eligibility and the benefit of claiming for every remaining FIG year.
13. FIG Claim Deadlines for 2026–27
HMRC provides a specific claim deadline.
A FIG claim generally must be made within 12 months after the normal 31 January Self Assessment filing deadline following the relevant tax year.
Example for 2026–27
| Event | Date |
|---|---|
| Tax Year Ends | 5 April 2027 |
| Normal Online Self Assessment Filing Deadline | 31 January 2028 |
| General FIG Claim Deadline | 31 January 2029 |
These dates assume the ordinary tax year and claim rules.
The claim deadline does not automatically postpone the normal tax return filing or payment deadline.
Other circumstances, including late notices to file, may affect amendment rules.
14. Can Foreign Losses Be Claimed Under FIG?
Claiming FIG relief has consequences for qualifying foreign losses.
HMRC explains that certain foreign capital losses and qualifying trading or property losses arising in a year covered by a FIG claim cannot be claimed for relief.
Relevant losses may also be unavailable for carry-forward or carry-back.
This matters for individuals with overseas investments or foreign business losses.
A person should not assume that FIG permits them to exempt profitable foreign transactions while claiming all associated foreign losses against UK income.
15. What Is the Temporary Repatriation Facility (TRF)?
The Temporary Repatriation Facility is a separate transitional measure for qualifying former remittance-basis users.
It addresses certain foreign income and gains arising before 6 April 2025.
The TRF operates for three UK tax years.
| Tax Year | TRF Rate |
|---|---|
| 2025–26 | 12% |
| 2026–27 | 12% |
| 2027–28 | 15% |
Eligible individuals may elect to designate qualifying historic foreign income and gains under the applicable TRF rules.
The designation and tax consequences must be analysed carefully.
FIG vs TRF
FIG: Relief for qualifying new foreign income and gains arising during eligible years from 6 April 2025.
TRF: Transitional reduced-rate treatment for certain previously accumulated foreign income and gains of qualifying former remittance-basis users.
These two regimes must not be confused.
16. What Happened to Pre-April 2025 Foreign Income?
Foreign income and gains that arose before 6 April 2025 under the old remittance-basis system may remain subject to historical remittance rules.
Simply transferring old overseas funds to the UK after the reform does not automatically make them tax-free.
The taxpayer must establish:
- When the income or gain arose.
- Whether the old remittance basis applied.
- Whether funds have been mixed with other amounts.
- Whether a TRF election is available.
- Whether the relevant remittance creates a taxable event.
Former non-dom taxpayers should obtain specialist advice before transferring significant historic offshore funds.
17. Does FIG Change UK Inheritance Tax?
The reform also changed the connection between UK residence and Inheritance Tax.
From 6 April 2025, the United Kingdom moved toward a residence-based system for the treatment of non-UK assets.
Broadly, long-term residence is important, including the test involving residence for at least 10 of the previous 20 tax years.
The relevant rules also contain provisions affecting individuals who leave the UK and certain trusts.
Important: The four-year FIG regime is principally an Income Tax and Capital Gains Tax relief. It is not a blanket exemption from UK Inheritance Tax.
Estate and trust planning require separate analysis.
18. How Does FIG Affect Overseas Pakistanis Living in the UK?
The FIG regime may be relevant to Pakistani nationals who move to the United Kingdom after many years of non-UK residence.
Potential examples include:
- Pakistani business owners relocating to London.
- Professionals moving to Britain while retaining Pakistani investments.
- Individuals receiving rental income from property in Pakistan.
- Investors holding foreign dividend-paying shares.
- People maintaining overseas bank deposits.
- Returning British expatriates with Pakistani business interests.
However, the tax treatment depends on the exact source of income and the individual's UK tax residence.
Example: Pakistani Rental Income and UK Employment
Suppose a new UK resident earns:
- UK employment income: £45,000.
- Qualifying net property income from Pakistan: £12,000.
A valid FIG claim may provide relief from UK tax on the qualifying Pakistani property income.
However, UK employment income remains taxable.
The person must also consider the loss of the UK Personal Allowance and the separate tax obligations in Pakistan.
The Pakistan–UK double taxation agreement may be relevant in other circumstances, but eligibility for FIG is determined under UK domestic legislation.
19. Common FIG Regime Mistakes to Avoid
- Assuming Pakistani nationality automatically qualifies someone.
- Confusing domicile with the new residence-based test.
- Ignoring the 10 consecutive tax-year non-residence requirement.
- Assuming all foreign income is automatically exempt.
- Failing to make a Self Assessment claim.
- Claiming ordinary FIG relief on foreign employment income without checking OWR.
- Forgetting that the Personal Allowance is lost.
- Assuming FIG provides four additional years after a temporary departure.
- Applying FIG to pre-6 April 2025 income.
- Confusing the TRF with FIG.
- Failing to report income on a source-by-source basis.
- Claiming foreign losses contrary to the relevant restrictions.
- Assuming FIG exempts UK employment income.
- Ignoring the effect on pensions, childcare or other tax calculations.
- Treating FIG as a complete UK Inheritance Tax exemption.
20. Final FIG Eligibility and Filing Checklist
Before claiming FIG relief, verify:
- UK tax residence for the relevant year.
- Previous 10 consecutive tax years of non-UK residence.
- First year of UK tax residence.
- Remaining qualifying FIG years.
- Nature and source of foreign income.
- Eligibility of overseas capital gains.
- Separate treatment of foreign employment income.
- Impact on Personal Allowance.
- Impact on the CGT annual exempt amount.
- Available tax reliefs and losses.
- Foreign taxes paid.
- UK Self Assessment filing requirements.
- Source-by-source disclosure.
- Claim submission deadline.
- Eligibility for TRF where historic offshore income exists.
- Supporting documents and residence evidence.
21. Watch Tax With Naeem — International Income Reporting
For general educational guidance on income tax returns, foreign income reporting, salary income, rental income and capital gains, visit the Tax With Naeem YouTube channel.
Related Video: Income Tax Return Filing in Pakistan — Salary, Rental Income, Capital Gains and Dividends Explained
https://www.youtube.com/watch?v=VX88o1N1AfA
This is a Pakistan tax filing tutorial and not a dedicated UK FIG or HMRC Self Assessment guide.
Readers should use HMRC's official rules for the UK tax residence and FIG calculations.
22. Official UK Government Sources
1. HMRC — Check Eligibility for the Four-Year FIG Regime
https://www.gov.uk/guidance/check-if-you-can-claim-the-4-year-foreign-income-and-gains-regime
2. HMRC — FIG Regime Self Assessment Helpsheet HS266 (2026)
3. HMRC — Residence and FIG Regime Manual
https://www.gov.uk/hmrc-internal-manuals/residence-and-fig-regime-manual/rfig41000
4. HMRC — FIG Claims and Reporting Requirements
https://www.gov.uk/hmrc-internal-manuals/residence-and-fig-regime-manual/rfig42100
5. HMRC — Temporary Repatriation Facility HS264
6. HMRC — Overseas Workday Relief
https://www.gov.uk/government/publications/globally-mobile-employees/overseas-workday-relief
7. HMRC — UK Tax Residence Guidance
https://www.gov.uk/government/collections/uk-tax-residence-guidance
8. AsaanTax.pk — International Taxation Guides
23. Conclusion: Who Benefits From the UK Four-Year FIG Regime?
The abolition of the UK's old non-dom remittance-basis system represents a major change in international personal taxation.
From 6 April 2025, eligible new UK tax residents can claim relief on specified foreign income and capital gains for up to four tax years.
To qualify, individuals must satisfy the relevant 10-year non-residence requirement and the other statutory conditions.
The relief is particularly relevant for individuals relocating to the UK while retaining overseas investments, rental properties or other qualifying foreign income sources.
However, it is not automatic. Claimants must use Self Assessment, report the relevant income and gains, consider the loss of personal allowances and distinguish FIG from Overseas Workday Relief and the Temporary Repatriation Facility.
The most important rule is that FIG relief depends on UK tax residence history and the nature of foreign income—not nationality or the former non-dom label.
For more international tax guides covering UK Income Tax, overseas assets, UAE taxation and Pakistan FBR rules, visit AsaanTax.pk.
Editorial Note: This article reflects HMRC guidance available as of 10 November 2026, including the 2026 FIG Self Assessment helpsheet and updated residence guidance.
Disclaimer: This article provides general educational information rather than individualized UK tax advice. Cross-border income, offshore trusts, employment, historic remittances and inheritance matters can involve complex rules. A qualified UK international tax adviser should review significant FIG or TRF claims.