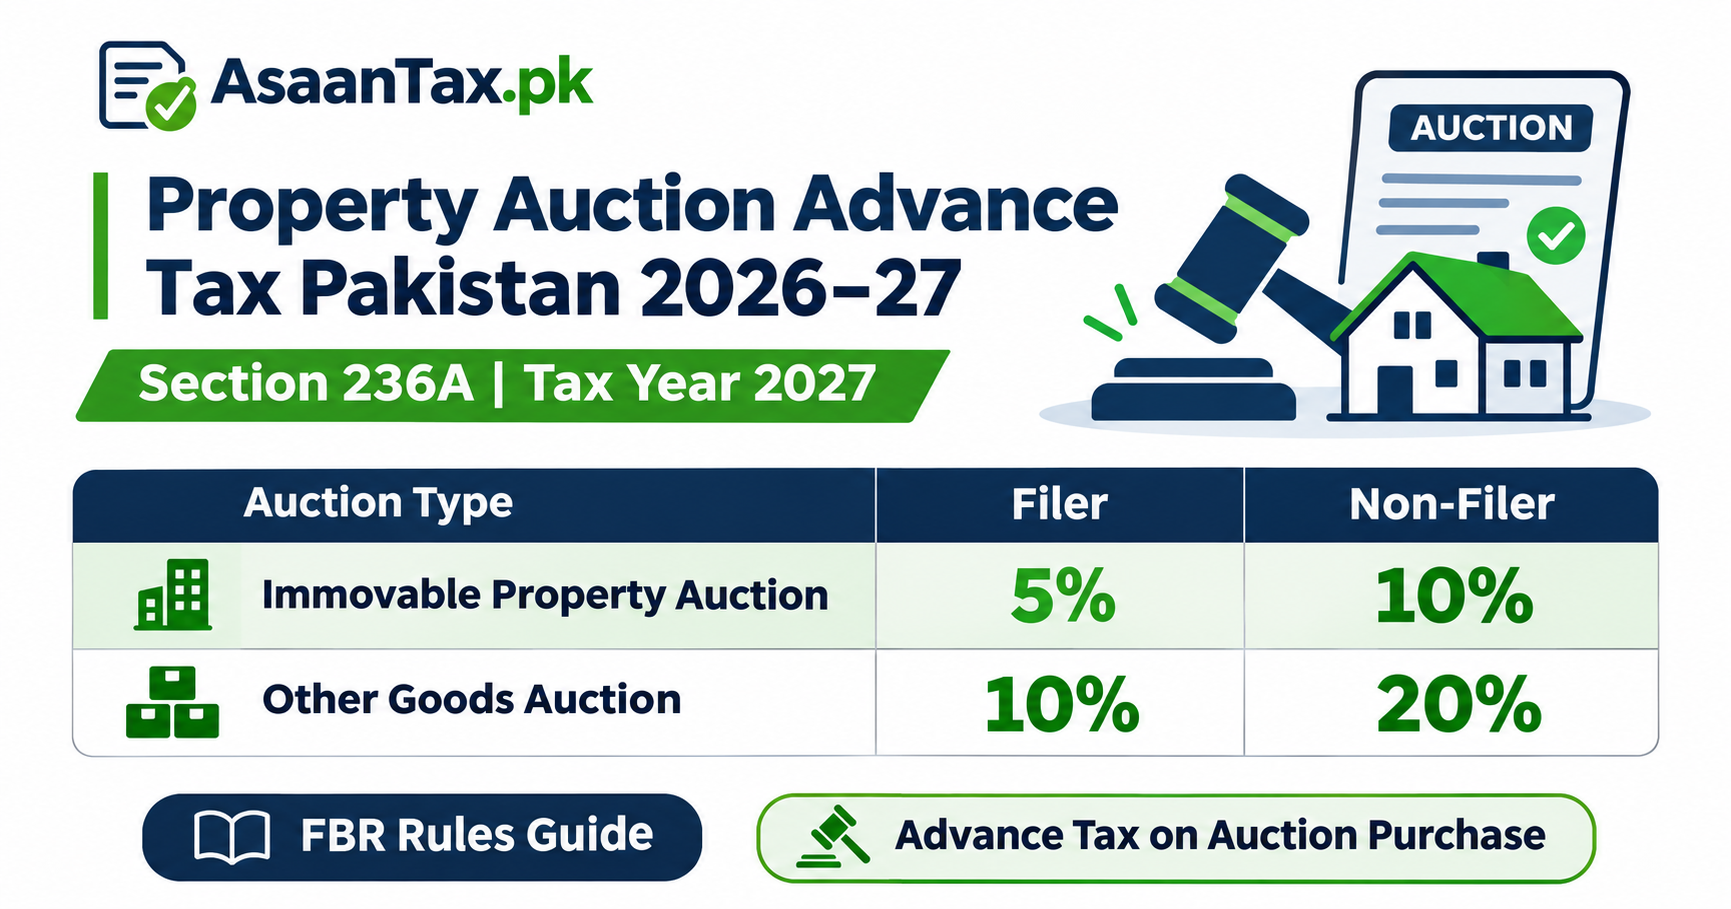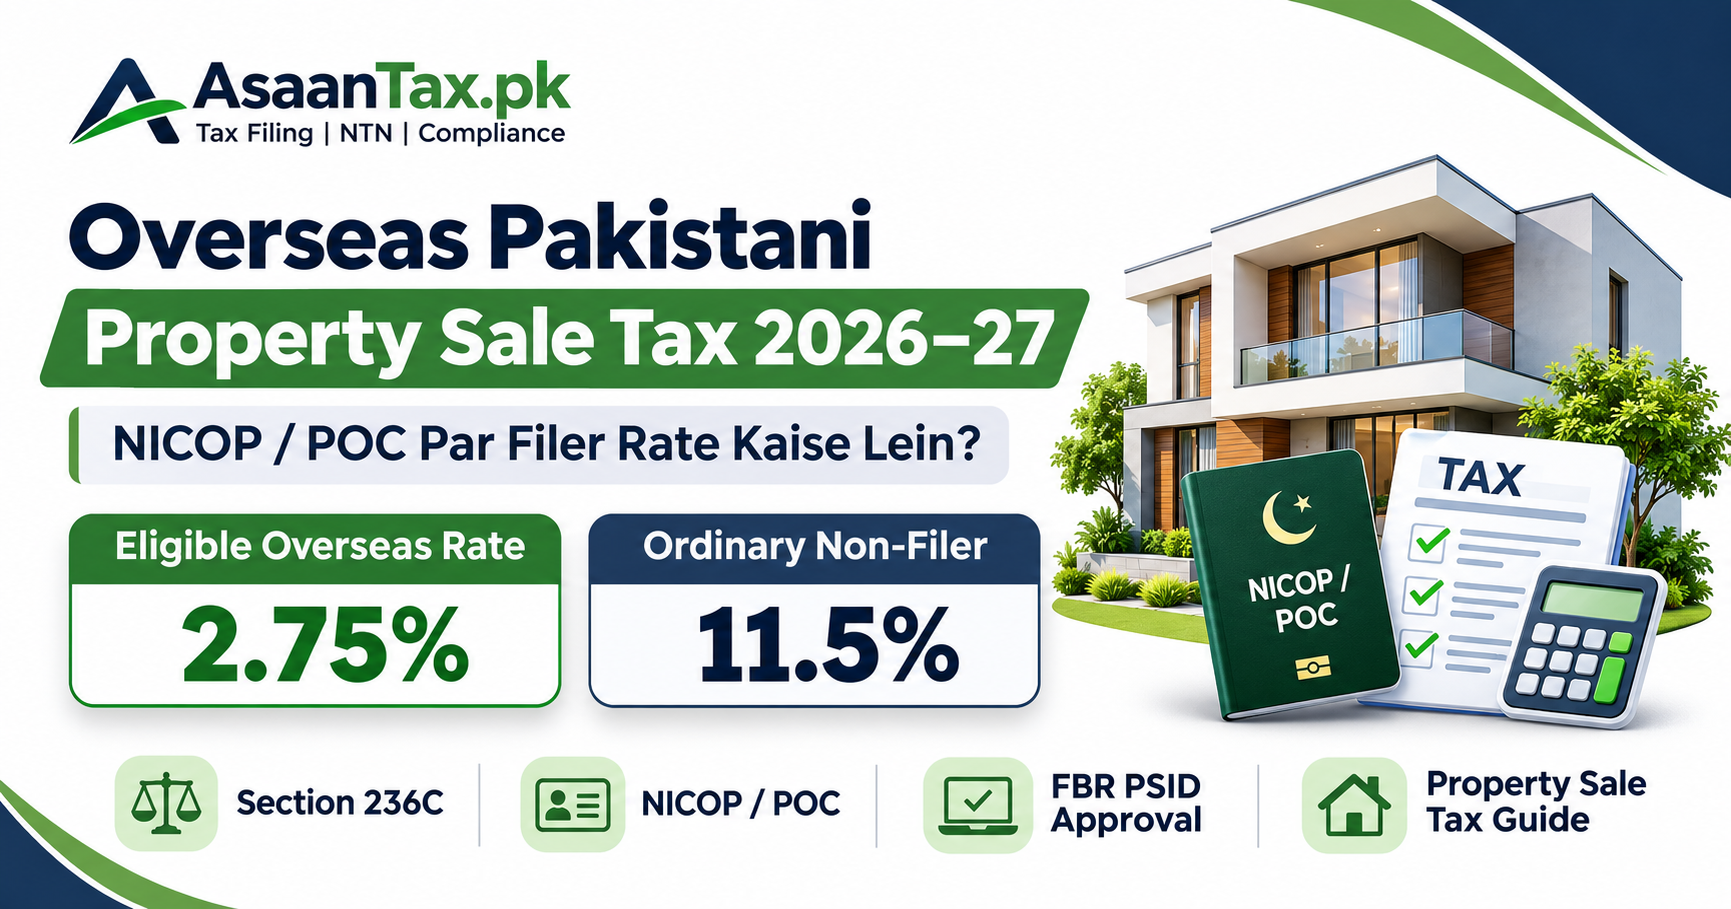
Is Inherited Property Taxable in Pakistan? Complete FBR Guide 2026–27
Published: November 9, 2026
Applicable Tax Year: 2027
Updated Legislation: Finance Act 2026
Relevant Law: Income Tax Ordinance, 2001
Inheriting a house, residential plot, commercial building, agricultural land or other property after the death of a family member is common in Pakistan. However, many legal heirs are unsure whether they must pay income tax when property is transferred into their names.
The good news is that Pakistan does not impose a separate federal inheritance tax merely because someone receives property through inheritance.
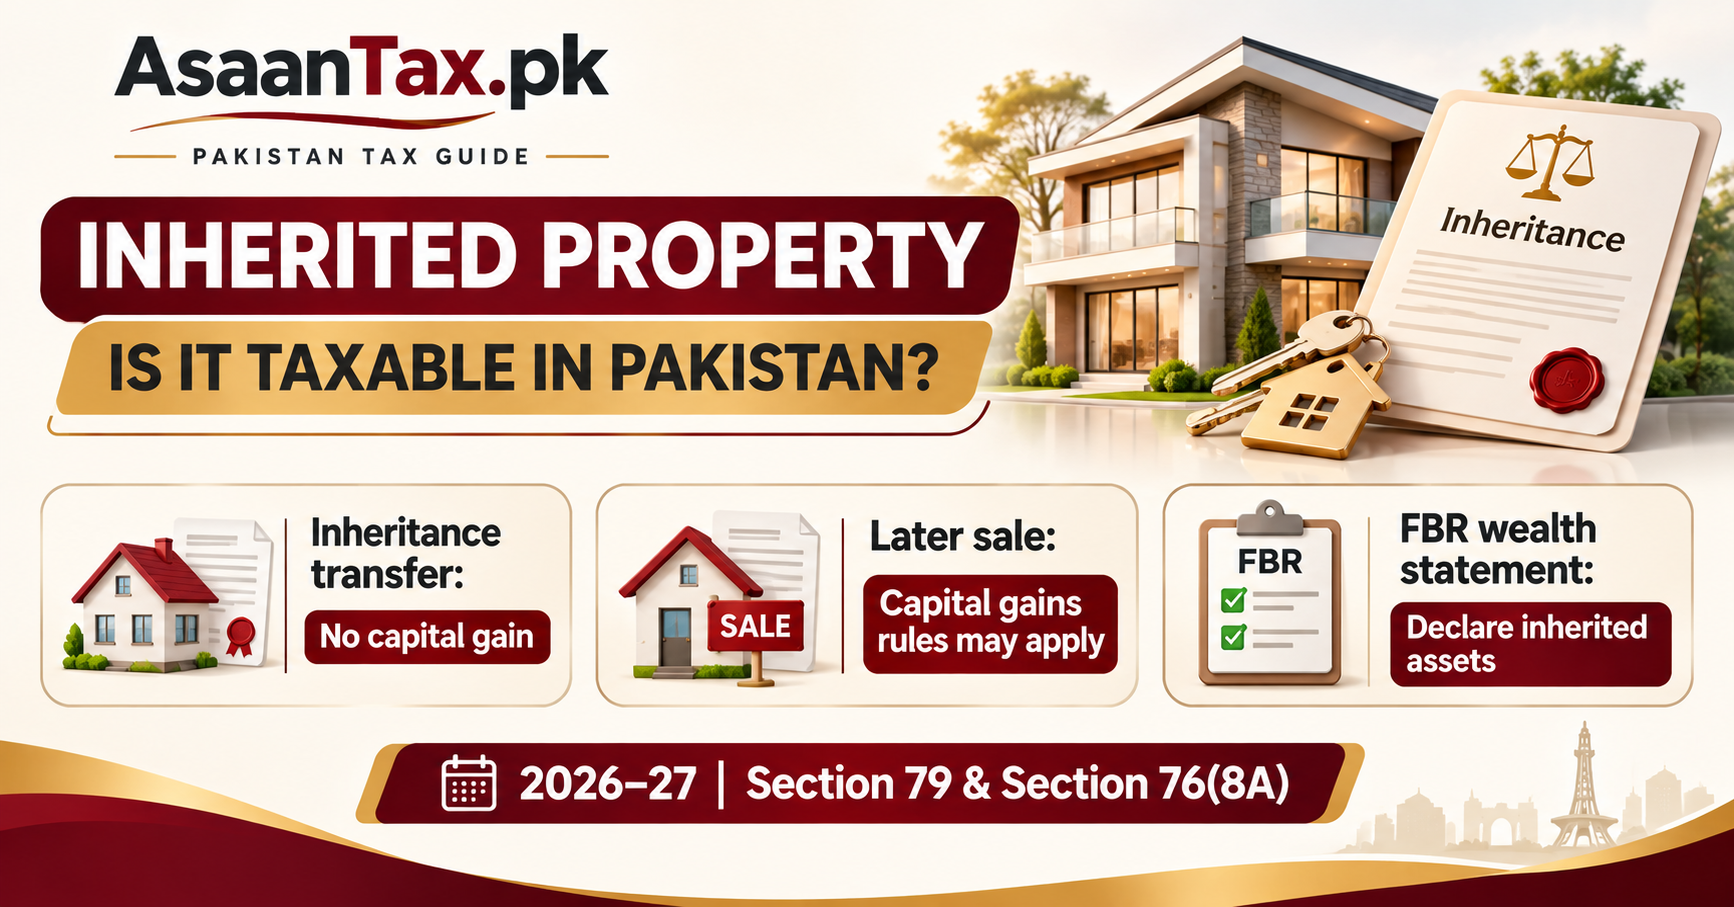
Under Section 79 of the Income Tax Ordinance, 2001, the transfer of an asset to a beneficiary following someone's death is generally treated as a non-recognition transaction for capital gains purposes.
However, receiving inherited property, transferring ownership records, declaring the asset in an FBR Wealth Statement, earning rental income and selling the property are different events with different legal consequences.
The Finance Act 2026 also introduced Section 76(8A), which provides a specific cost rule for inherited immovable property.
This complete guide explains inheritance tax rules in Pakistan for 2026–27, the process of transferring property to legal heirs, FBR declaration requirements, capital gains tax on subsequent sales, and important precautions for overseas Pakistanis.
1. Is Inherited Property Taxable in Pakistan?
Generally, receiving property through inheritance does not itself create a taxable capital gain under Pakistan's federal income tax law.
For example, if a father dies and his residential house passes to his legal heirs, the transfer arising from his death ordinarily does not create a recognized capital gain merely because the heirs receive ownership.
The legal position is primarily governed by Section 79 of the Income Tax Ordinance, 2001.
However, the absence of inheritance tax does not automatically eliminate other obligations, including documentation, land record fees, provincial property taxes, tax on rental income or capital gains tax when the property is later sold.
Quick Tax Comparison
| Transaction or Event | General Tax Treatment |
|---|---|
| Receiving property through inheritance | No recognized capital gain on transmission under Section 79 |
| Recording inheritance mutation | Administrative or provincial fees may apply |
| Declaring inherited property in a Wealth Statement | Reporting obligation where applicable; not a separate inheritance tax |
| Renting out inherited property | Rental income may be taxable |
| Selling inherited property | Capital gains and advance withholding rules may apply |
| Holding property after inheritance | Provincial property taxes or other relevant charges may apply |
| Family settlement following death | May qualify under the 2026 clarification to Section 79 |
The actual treatment depends on the circumstances and applicable legislation.
2. Section 79: Why Is Inherited Property Generally Not Taxed on Transfer?
Section 79 is one of the most important provisions for inherited property in Pakistan.
Under Section 79(1)(b), no gain or loss is recognized for income tax purposes when an asset is transferred to an executor or beneficiary because of someone's death.
This is commonly known as a non-recognition rule.
Example: A House Inherited From a Father
Assume a father owned a house in Lahore.
After his death, ownership passes to his legal heirs according to the applicable inheritance law.
Even if the property's market value has increased over time, the transmission following death generally does not trigger a recognized capital gain under Section 79.
The heirs must still establish their legal entitlement and complete applicable ownership documentation.
Important Change in Finance Act 2026
The Finance Act 2026 added an explanation to Section 79 clarifying that the transmission of immovable property to beneficiaries following death also includes property transmission through a family settlement among family members consequent upon that death.
This is important for families arranging the distribution of inherited assets.
However, an ordinary commercial sale or an independent gift should not automatically be treated as a qualifying inheritance settlement.
3. Section 76(8A): New Inherited Property Cost Rule for 2026–27
One of the most important developments in the Finance Act 2026 concerns the cost of immovable property received through inheritance.
Section 76(8A) provides that where an individual acquires immovable property through inheritance, the cost of the property in that individual's hands is determined using the fair market value specified through the reference to Section 68(5), at the time the property is transferred to the beneficiary.
Why Does This Matter?
The cost of an asset is important when calculating a capital gain upon its later sale.
A higher legally recognized acquisition cost may result in a lower taxable gain, while a lower recognized cost can result in a larger gain.
However, the statutory cost treatment must be applied carefully.
Section 79(3) also contains a general carryover-cost rule for non-recognition transfers. The interaction of this provision with the new, more specific Section 76(8A) rule should be evaluated when preparing an actual capital gains calculation.
Taxpayers should not automatically use an estimated commercial market price without checking the legally prescribed valuation and the facts of the inheritance.
4. Do Legal Heirs Have to Pay Tax When Property Is Transferred?
The inheritance itself generally does not create a recognized capital gain under Section 79.
However, property transfer and land record procedures may involve other charges.
These can include:
- Land record service charges.
- Mutation or Intiqal processing fees, where applicable.
- Documentation and certified record fees.
- Registration or stamp charges where the particular instrument and provincial law require them.
- Housing society or development authority transfer charges where applicable.
- Professional documentation expenses.
Not every charge applies to every inheritance.
Important: Ordinary sale or purchase tax rates should not automatically be applied to a genuine transmission by inheritance.
The correct treatment depends on the legal nature of the transfer and the relevant federal and provincial legislation.
5. How to Transfer Inherited Property in Pakistan
When property passes to legal heirs, the ownership record should be updated using the process applicable to the relevant province, authority or housing society.
For land recorded through the Punjab Land Records Authority, the process generally involves inheritance mutation, also called Intiqal-e-Wirasat.
Step 1: Obtain the Death Certificate
Obtain the relevant death registration certificate for the deceased property owner.
Step 2: Identify All Legal Heirs
Determine the legal heirs and their respective shares according to the applicable succession and personal law.
All entitled heirs must be considered.
Step 3: Collect Property Documents
Gather available records such as:
- Property ownership documents.
- Existing Fard or land record.
- Registered title documents, where relevant.
- CNIC details of the deceased and legal heirs.
- Family Registration Certificate or other family relationship evidence.
- Relevant death certificate.
- Succession-related documents, where legally necessary.
Step 4: Visit the Relevant Authority
Depending on the property, approach the appropriate:
- Arazi Record Centre.
- Revenue office.
- Development authority.
- Housing society transfer office.
- Other competent land or property registration authority.
Step 5: Apply for Inheritance Mutation
Submit the documents and request the relevant change in ownership records.
The authority may verify family relationships, legal entitlement, property details and required formalities.
Step 6: Complete Verification
Comply with the applicable verification and approval process.
Step 7: Obtain Updated Records
After approval, obtain the updated mutation or ownership record showing the legal heirs and their respective interests.
Important: Punjab, Sindh, Khyber Pakhtunkhwa, Balochistan, Islamabad and private housing authorities may follow different procedures.
6. What Are the Inheritance Mutation Fees in Punjab in 2026?
The Punjab Land Records Authority revised several land record service charges for FY 2026–27.
Reported general service charges include:
| Service | Reported PLRA Service Charge |
|---|---|
| Ordinary mutation service | Rs 1,200 |
| Mutation processed through a bank | Rs 2,100 |
| Express mutation service | Rs 11,200 |
| Standard copy of relevant land record | Rs 900 |
| Express copy of relevant land record | Rs 4,000 |
These are general service charges, not necessarily the complete fee payable for an inheritance mutation.
The schedule does not establish one universal inheritance transfer cost for every property.
Additional government charges, exemptions and transaction-specific requirements may apply.
Punjab also has protections concerning the inheritance rights of women, including specific measures regarding inheritance mutation and related charges.
Before making payment, obtain the official fee calculation or challan from the relevant authority.
7. Must Inherited Property Be Declared in the FBR Wealth Statement?
Where a taxpayer is required to submit a Wealth Statement under Section 116, inherited assets should be properly reflected in the relevant reporting records.
An inherited house, plot, commercial property or agricultural land can affect the taxpayer's wealth position.
The source of acquisition should be correctly documented as inheritance rather than falsely described as a cash purchase funded by current-year income.
Example: Property Worth Rs 15 Million
Suppose an individual inherits a residential property with a relevant reportable value of Rs 15 million.
The individual should determine:
- The date of acquisition through inheritance.
- Their actual ownership share.
- The appropriate value for the relevant tax reporting schedule.
- The nature of the asset.
- The source of acquisition.
- The supporting inheritance documents.
The correct method of reporting may depend on the version of the IRIS form and the taxpayer's previous Wealth Statements.
Important: The value used for wealth statement reporting is not necessarily identical to the property's valuation for capital gains purposes.
Accurate records are essential to avoid inconsistencies.
8. Can FBR Question an Inherited Property That Was Not Declared?
Yes. If a taxpayer owns substantial assets that are not adequately explained in their tax records, FBR may examine the source of acquisition under applicable legal provisions.
Section 111 of the Income Tax Ordinance deals with certain unexplained income, assets, investments and expenditure.
A genuine inheritance can provide a legitimate explanation for an asset, but the taxpayer should maintain evidence supporting that explanation.
Useful supporting records include:
- The deceased person's death certificate.
- Relevant inheritance or succession documents.
- Mutation and land ownership records.
- Proof of relationship with the deceased.
- Information about the deceased owner's title.
- Evidence of the taxpayer's share.
- Relevant documentation for family settlements.
Failure to maintain records can make future tax inquiries more difficult.
The existence of an inherited asset does not automatically mean the taxpayer has concealed taxable income.
9. Is Capital Gains Tax Payable When Inherited Property Is Sold?
Capital gains tax may apply when inherited property is subsequently sold.
The reason is that the sale is a separate transaction from the original inheritance.
Although Section 79 provides non-recognition treatment for the transmission following death, an eventual sale by the beneficiary may result in a taxable capital gain under Section 37.
The applicable tax treatment depends on factors including:
- The property's legally relevant acquisition date.
- The date of sale.
- The applicable capital gains regime.
- The recognized cost under current law.
- The sale consideration and relevant statutory valuation.
- The taxpayer's applicable category.
- Available exemptions or special provisions.
General Capital Gain Calculation
Capital Gain = Relevant Disposal Consideration − Legally Allowable Cost
For inherited immovable property, the specific cost rule introduced through Section 76(8A) must be considered alongside other applicable statutory provisions.
Example: Sale of an Inherited House
Suppose an individual inherits a house and its legally relevant cost for illustration is Rs 12 million.
The individual later sells the house for Rs 16 million.
| Description | Amount |
|---|---|
| Illustrative Recognized Cost | Rs 12,000,000 |
| Illustrative Sale Consideration | Rs 16,000,000 |
| Illustrative Capital Gain | Rs 4,000,000 |
The mathematical gain is Rs 4 million.
However, the actual capital gains tax cannot be determined from this illustration alone.
It requires the applicable acquisition-date rules, tax rate, statutory cost valuation and other relevant legal conditions.
A gain of Rs 4 million does not mean that Rs 4 million is the tax payable.
10. Is Withholding Tax Deducted When Inherited Property Is Sold?
When an inherited property is sold, the ordinary property sale withholding tax rules may become relevant.
Section 236C deals with advance income tax collection from sellers of immovable property.
The applicable rate depends on the transaction date, taxpayer classification, value and relevant statutory schedule.
The eventual purchaser may separately fall under Section 236K.
Important Difference
Inheritance transfer: The property passes to legal heirs following death.
Property sale: A legal heir sells their inherited interest to a buyer in return for consideration.
These are separate legal events.
The fact that an inherited property was initially received without recognized capital gain does not automatically make its subsequent sale exempt from advance income tax.
11. What If the Inherited Property Is Rented Out?
A person receiving inherited property may decide to rent it to tenants.
In such cases, the inheritance itself is different from the subsequent rental income.
The rental income may be chargeable under the applicable income tax provisions, including Sections 15 and 15A.
The tax treatment depends on the taxpayer's rental income, applicable deductions, legal provisions and any relevant withholding obligations.
Example
Suppose an individual inherits a commercial shop and receives monthly rent of Rs 80,000.
Annual gross rental receipts would be:
Rs 80,000 × 12 = Rs 960,000
This amount represents gross annual rent before applying the relevant legal computation rules.
The actual tax liability must be calculated using applicable income tax legislation.
12. Is Agricultural Land Received Through Inheritance Tax-Free?
Receiving agricultural land through genuine inheritance generally benefits from the Section 79 non-recognition rule.
However, owning agricultural land and earning agricultural income are different matters.
Agricultural income may fall under provincial tax laws, subject to relevant legal provisions.
Similarly, selling agricultural land or transferring it through a separate taxable transaction may require additional analysis.
The fact that the property is agricultural land does not eliminate every possible tax or documentation requirement.
13. What Happens When Property Is Inherited by Several Brothers and Sisters?
Inheritance often involves multiple legal heirs.
For example, a deceased person may leave property to a surviving spouse, sons, daughters and other eligible relatives.
The actual legal shares depend on the relevant succession rules and family circumstances.
The inheritance mutation should correctly reflect all entitled beneficiaries.
An heir should generally report only the property interest that legally belongs to them, not automatically the full property value.
Example
If a property is owned jointly by multiple heirs, each person's interest must be determined before reporting ownership or calculating tax on a subsequent sale.
The exact division cannot be assumed without considering all eligible heirs and the governing law.
Women and daughters must not be excluded from their lawful inheritance rights.
14. What Is the Tax Treatment of a Family Settlement After Death?
The Finance Act 2026 inserted an important clarification into Section 79.
Under the amended provision, transmission of immovable property to beneficiaries following death can include transfers through family settlements among family members consequent upon the death of the owner.
This may assist families in arranging the distribution of inherited assets.
However, the settlement must genuinely satisfy the legal conditions.
Transactions that are actually independent sales, unrelated gifts or commercial exchanges should not automatically be described as inheritance settlements.
Families should retain proper written documentation and obtain legal advice where ownership interests are disputed.
15. Can Overseas Pakistanis Inherit Property Without Paying Inheritance Tax?
Overseas Pakistanis can inherit property in Pakistan according to the applicable succession law.
The Section 79 non-recognition treatment generally concerns the nature of transmission on death rather than simply the heir's residence.
However, non-resident heirs should consider additional matters:
- Documentary proof of legal inheritance.
- CNIC, NICOP or other relevant identity documentation.
- Representation and authorization requirements.
- Property registration procedures.
- Pakistan-source rental income.
- Tax implications of a future property sale.
- Banking and remittance documentation.
- Relevant tax treaty considerations, where applicable.
A person living abroad should not assume that every subsequent property transaction is automatically tax-free.
16. Is Section 7E Tax Still Applicable in Tax Year 2027?
Section 7E previously introduced tax on certain deemed income from immovable property.
However, the Finance Act 2026 omitted Section 7E from the Income Tax Ordinance.
Therefore, older articles describing Section 7E as an active general deemed-property-income tax for Tax Year 2027 should not be relied upon without checking the updated legislation.
This does not eliminate separate taxes on actual rental income, taxable capital gains or applicable provincial property taxation.
It is important to distinguish these different legal provisions.
17. Common Mistakes When Reporting Inherited Property
Taxpayers should avoid the following mistakes:
- Assuming inheritance and a subsequent sale are always tax-free.
- Failing to update legal ownership records.
- Omitting inherited assets from a required Wealth Statement.
- Reporting the entire inherited property when only a share belongs to the taxpayer.
- Using the wrong property acquisition date.
- Applying an unsupported market value as the recognized capital gains cost.
- Ignoring Section 76(8A) of the updated Income Tax Ordinance.
- Confusing inheritance mutation with a commercial property sale.
- Ignoring applicable rental income reporting.
- Failing to retain death and succession documents.
- Excluding legally entitled female heirs.
- Applying outdated Section 7E guidance to Tax Year 2027.
Correct documentation can prevent costly tax and ownership disputes.
18. Final Checklist for Inherited Property Owners
Before reporting, transferring or selling inherited property in Pakistan, complete these checks:
- Obtain the deceased owner's death certificate.
- Identify all legal heirs and their shares.
- Collect the existing property ownership documents.
- Determine whether succession-related documentation is required.
- Apply for the relevant inheritance mutation.
- Verify the updated land record.
- Determine the property's acquisition date and applicable valuation.
- Keep supporting evidence of inheritance.
- Declare the asset where a Wealth Statement is required.
- Apply Section 76(8A) where relevant to a subsequent sale.
- Verify any applicable capital gains tax and withholding tax.
- Retain all official documents and receipts.
19. Watch Tax With Naeem — Property Capital Gains Tax Explained
For a practical explanation of property capital gains and how the acquisition date affects income tax in Pakistan, watch this relevant video from Tax With Naeem.
Video Title: Property Gain Tax Relief 2026 | Lahore High Court Decision on Super Tax | Tax With Naeem
Watch on YouTube:
https://www.youtube.com/watch?v=bh4qt46j3z4
This video discusses capital gains tax treatment of older properties and related tax issues.
It is useful supplementary content for understanding property taxation, but it is not a dedicated inheritance mutation tutorial.
Readers should use the updated Finance Act 2026 provisions for inherited property and seek case-specific guidance when calculating gains.
20. Official Sources and References
1. Federal Board of Revenue — Income Tax Ordinance, 2001
Official consolidated legislation amended up to June 30, 2026.
https://www.fbr.gov.pk/Categ/Income-Tax-Ordinance/326/1000
Relevant sections include:
- Section 37 — Capital Gains.
- Section 68 — Fair Market Value.
- Section 75 — Disposal and Acquisition of Assets.
- Section 76(8A) — Cost of Inherited Immovable Property.
- Section 79 — Non-Recognition Rules.
- Section 111 — Unexplained Income or Assets.
- Section 116 — Wealth Statement.
- Section 236C — Advance Income Tax on Property Sales.
- Section 236K — Advance Income Tax on Property Purchases.
2. Punjab Land Records Authority
https://www.punjab-zameen.gov.pk/
For inheritance mutation, land records and provincial procedures.
3. Federal Board of Revenue — IRIS
For applicable income tax returns and Wealth Statements.
4. AsaanTax.pk — Wealth Statement Reconciliation Guide
https://www.asaantax.pk/blog/wealth-statement-reconciliation-unreconciled-amount-zero
5. AsaanTax.pk — Income Tax Guides
6. Tax With Naeem — Property Capital Gains Video
https://www.youtube.com/watch?v=bh4qt46j3z4
21. Conclusion: Do You Have to Pay Tax on Inherited Property in Pakistan?
Receiving property through genuine inheritance generally does not create a recognized capital gain under Section 79 of Pakistan's Income Tax Ordinance.
The Finance Act 2026 further clarified the treatment of qualifying family settlements after death.
However, inheritance does not eliminate the need for ownership documentation, applicable provincial charges, proper tax reporting or taxes arising from later transactions.
A subsequent sale may trigger capital gains tax and advance withholding tax. Rental income earned from inherited property may also be taxable.
The introduction of Section 76(8A) makes the valuation of inherited immovable property especially important for Tax Year 2027.
Property owners should preserve their inheritance documents, identify their legal shares, complete the relevant mutation procedures and ensure that their FBR records are accurate.
For more helpful guides on Pakistan property taxation, inheritance, capital gains tax, Wealth Statements and FBR compliance, visit www.asaantax.pk.
Editorial Note: This article reflects federal tax legislation amended through June 30, 2026. The relationship between the new Section 76(8A) cost rule and the general Section 79 carryover-cost rule may require professional interpretation in individual cases.
Disclaimer: This guide provides general educational information and does not constitute legal or personalized tax advice. Provincial property procedures, succession rights, valuation, residency, and tax liabilities depend on the specific facts and applicable law.